AI’s Big Spenders Are Raising Cash. Here’s the Bank That Gets Paid Either Way.

 |
| By Al Qureiyeh |
Do you own Meta Platforms (META) or Alphabet (GOOGL) through an index fund?
Then you were just asked to help pay for the AI buildout.
Meta Platforms priced a stock sale Monday that could reach $97.5 billion. Alphabet did the same in June, and its shares now sit about 11% below the price of that sale.
Also on Monday, Anthropic (Pending: ANT) filed to go public with $16.3 billion of revenue in the first half of the year.
The AI buildout is no longer paid for out of profits.
It is paid for with new shares and new debt.
And we can buy the company collecting the fees in cash.
Let me explain …
Meta's Sale Comes in 3 Parts
The first is $25 billion of common stock, then a preferred stock with a fixed dividend, then more share sales from early next year.
The common stock was sold forward, which means Meta receives no cash until the shares settle, as late as November 2027.
Investors read it as dilution, and the stock fell 1.9% Monday.
Anthropic's filing showed the other side.
Its revenue is many times what it was a year earlier, and the chipmakers, Nvidia, Broadcom and their peers, rallied 2.8%.
Monday's rally was in the companies that sell the chips, not the ones issuing stock and borrowing to buy them. More stocks set new lows than new highs.
SpaceX (SPCX), meanwhile, is arranging about $40 billion of debt to buy Nvidia chips.
Related story: SpaceX Secures $40B for Nvidia Chips. Here’s Who’s Paying for Its AI Buildout.
Why the Dilution Worry Is Real
First, the money. Meta has the cash on hand to cover this year's spending without selling stock.
It is selling anyway, because next year's spending plans run past what the business produces.
Second, the precedent. Alphabet's June sale was followed by a fall, and the shares still sit below the sale price.
Third, the fear in the options market: Demand for protection on the largest technology stocks is at a one-year high.
We grant all three.
The bulls are right about one thing, too: Anthropic's numbers say the demand for AI is real.
What Weiss Is Saying
Weiss rates Morgan Stanley (MS) B, a BUY, with Reward rated B and Risk rated C+.
Nvidia is B+, a BUY, and Meta is B-, a BUY.
Goldman Sachs (GS), the other bank on both deals, is C+, a HOLD.
Weiss Ratings Daily ran "SpaceX Secures $40B for Nvidia Chips. Here's Who's Paying for Its AI Buildout." on Oct. 27.
It named the lenders and the banks behind the money: Apollo Global (APO), Goldman, BlackRock (BLK) and KKR & Co. (KKR).
Who’s paying for SpaceX’s AI buildout is the right question to ask.
But for us, that raised a different question …
Who Is Lending?
We went looking for the company that gets paid in cash, and we expected it to be Nvidia.
However, its own filing shows otherwise …
In the six months to July, the money Nvidia's customers owe it rose 64%.
Five customers account for 70% of that, and some get up to a year to pay.
Over the same six months, Nvidia's stakes in private companies — among them OpenAI and Anthropic (Pending: ANT) — the buyers of its chips, grew by about $29 billion.
That is about 41% of the cash its business generated.
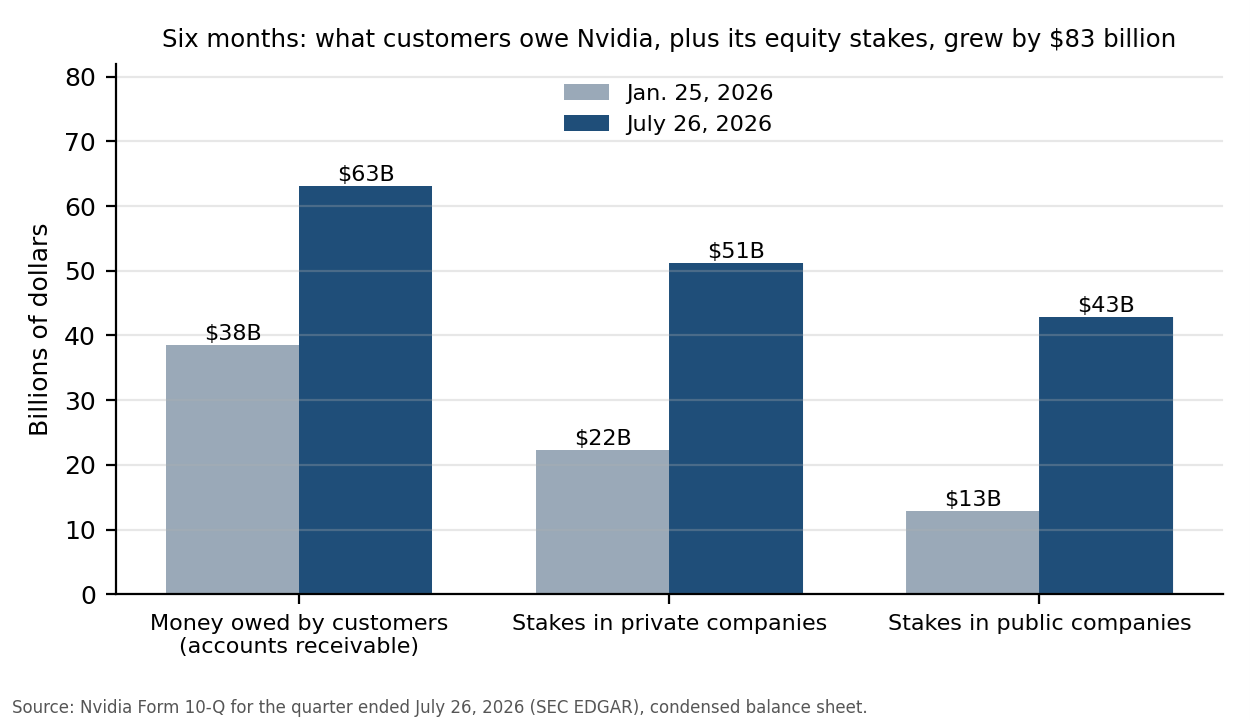
And $23.7 billion of its reported income over those six months was gains on its stakes in other companies, not chip sales.
Nvidia has also told Meta it may buy some of the new shares, together with AMD and Broadcom.
So, the chip seller is financing its buyers. If you own Nvidia, we suggest you hold it and do not add.
But if you are looking to buy, remember …
The Banks Get Paid Either Way
A bank earns its fee when the deal gets priced, in cash, whatever the stock does afterward.
Morgan Stanley (MS) and Goldman Sachs ran Meta's sale. They are also at the top of Anthropic's filing.
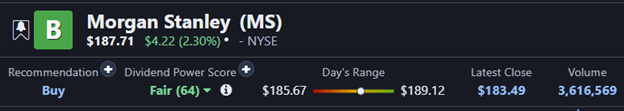
Through September, Morgan Stanley earned more than $1 billion of fees from stock sales, the first time since 2021.
Industry fees from new listings nearly doubled this year. The two biggest deals of the moment, Meta and Anthropic, run through the same two banks.
What could work against it: The bank's own stock-sale fees fell last quarter, so they are uneven from quarter to quarter.
MS shares have also lagged the market since June.
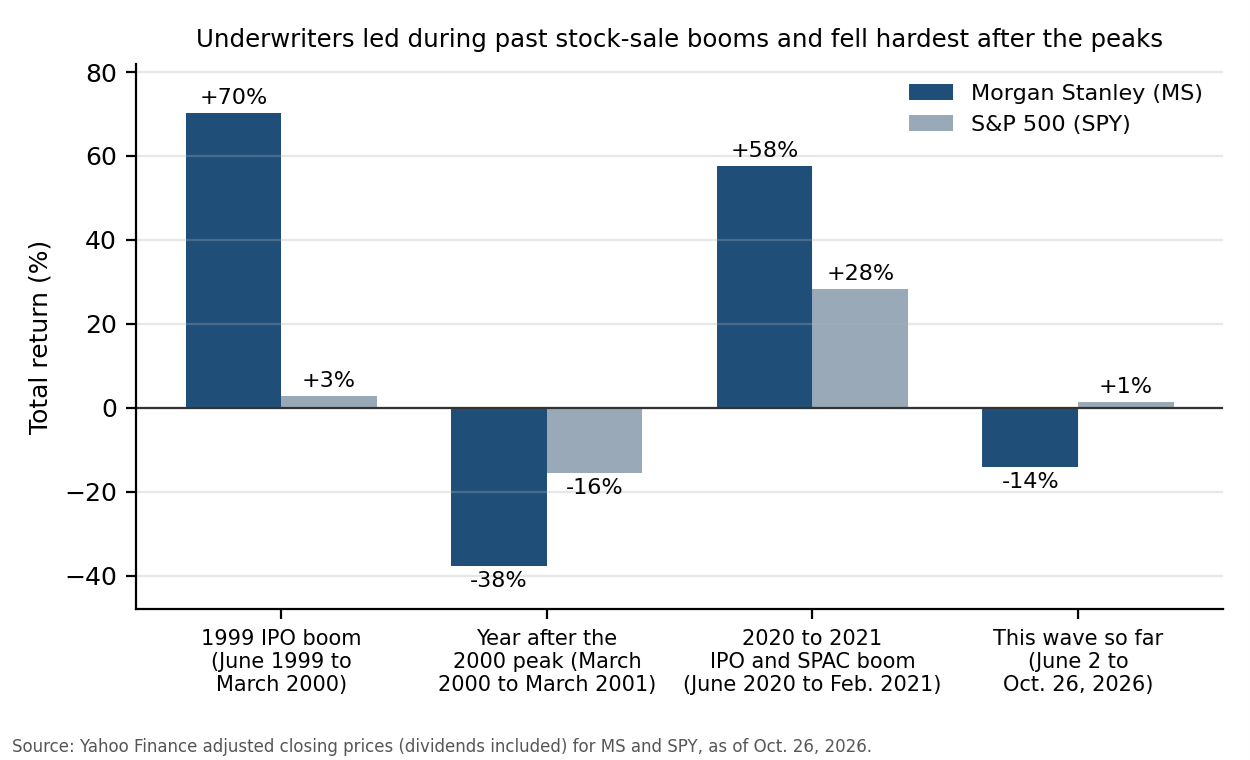
In the stock-sale booms of 1999 and 2020, Morgan Stanley beat the market by a wide margin. In the year after the 2000 peak, it fell 38% against 16% for the market.
You could wait and buy Anthropic’s IPO, though I suggest following my colleagues Chris Graebe and Sean Levine’s lead at Day One Syndicate when it comes to discovering investable IPOs.
They’re poring of the data right now to see whether Anthropic can earn that title.
But Morgan Stanley is something you could buy today, to get ahead of the Anthropic road show that’s set to start in earnest in November.
MS is a trade for this run of stock sales, not a permanent holding. We'd sell it when the big issuers stop coming.
It pays $1.15 a share each quarter while you wait. Based on Monday's closing price of $183.49, that works out to about 2.5% a year.
Our time frame runs through Anthropic's listing and Morgan Stanley's Jan. 14 report.
Here’s What Else We're Watching
First, Wednesday's reports from Microsoft and Alphabet. If either cuts next year's spending plans, the stock-sale wave slows, and we'd say so.
Second, Anthropic's listing. If it is delayed or priced below its last private round, the fee pipeline shrinks and we'd revisit.
Third, Nvidia's mid-November report. If the money customers owe it keeps rising faster than sales, we'd revisit the hold.
Fourth, Meta against its offer price. A close below it in the first week would say the market will not fund the next sale on these terms.
Take care,
AL Qureiyeh