Gasoline Drove Half of September's 0.6% Inflation Jump. Valero Keeps the Diesel Margin.

 |
| By Al Qureiyeh |
If you've filled up lately, you already know what drove the latest inflation report. You're still paying about $4.33 a gallon, roughly $1.27 more than a year ago.
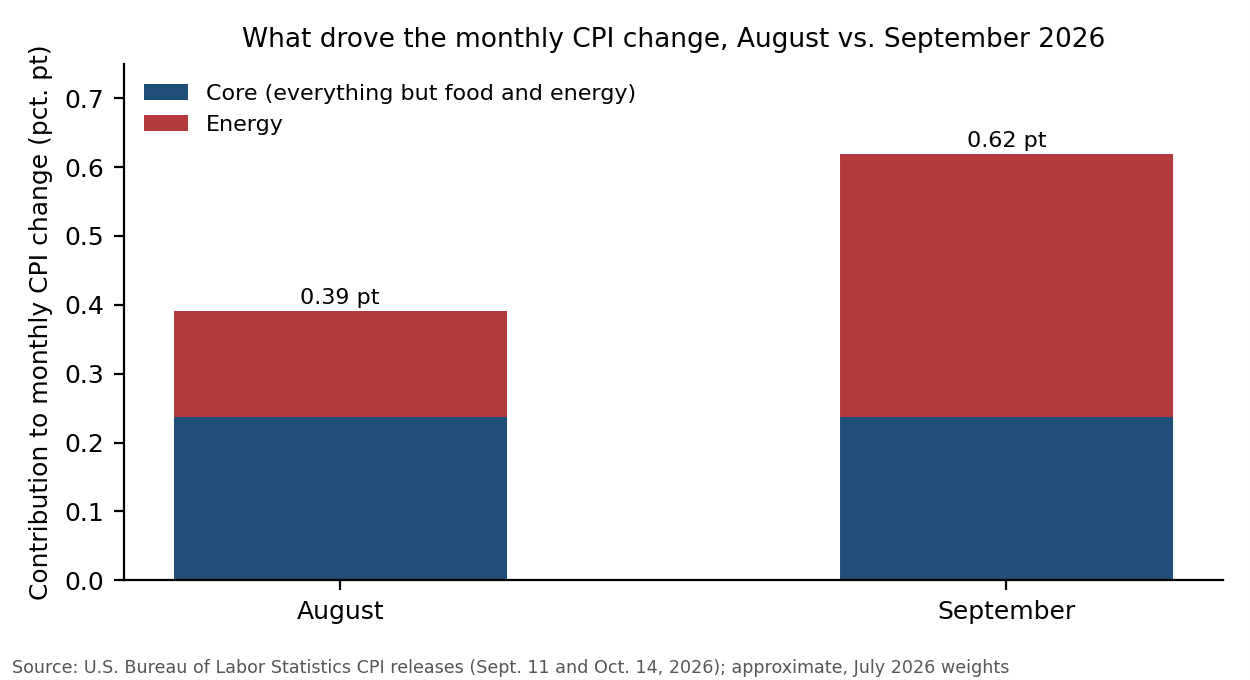
On Oct. 14, the Labor Department said consumer prices rose 0.6% in September, and inflation over the past year rose a little faster than expected. Gasoline accounted for more than half of the monthly increase, in the government's own words.
If you've tried to profit from high fuel prices through oil producers like Exxon Mobil (XOM) and Chevron (CVX), you're buying near their highs, at prices at or near Wall Street's average targets. The bigger margin is at the refinery: diesel earned refiners about $109 a barrel over crude in September, up from $95 in August.
The oil field isn't where the squeeze is. The refinery is, and I'd own the best-rated refiner heading into what analysts expect to be a record quarter.
What Happened
The headline number was what economists expected. The surprise was the rest of the basket: prices excluding food and energy rose a bit faster than economists forecast, and airfares, which rise with jet fuel prices, jumped. That is the part the Fed watches most closely.
There were no revisions to earlier months and no change in how the government measures prices.
Markets took the number at face value for short-term rates. Traders' odds of a Federal Reserve (Fed) rate hike at the Oct. 28 meeting more than doubled, by CME Group's futures-based measure. Long-term Treasury yields rose less and gave back part of the move.
On my scorecard, if you bought Alphabet (GOOGL) at Monday's close, you're slightly ahead of the market. If you avoided CoreWeave (CRWV), Oklo (OKLO) and NuScale Power (SMR), you sidestepped falls of as much as 19%.
Nvidia (NVDA) and the Technology Select Sector SPDR Fund (XLK) are down a little since Oct. 8, and Eaton (ETN) and GE Vernova (GEV) more since Oct. 6. We hate taking losses, but their BUY ratings haven't changed.
Why the Rate-Hike Crowd Is Half Right
Most of what's being written about this report leans toward higher interest rates, and two worries are real.
First, a Fed rate hike on Oct. 28 is now a real possibility. A hike makes borrowing more expensive for everyone.
Second, inflation is spreading past the pump. Services prices rose faster than in August, and airfares pass fuel costs through to travelers.
Where the crowd overreaches is the idea that the fuel part keeps building. Crude oil is already well off its September high, and global supply rose sharply in September, according to the International Energy Agency (IEA).
Weiss Rates the Refiners Highest in Energy
Weiss rates every oil name I checked a BUY. The three big refiners, Marathon Petroleum (MPC), Valero (VLO) and Phillips 66 (PSX), are all "B+."
The producers rate a notch lower: Exxon and Chevron "B," ConocoPhillips (COP) "B-." The Energy Select Sector SPDR Fund (XLE), which holds all of them, is "B," a BUY.
The Squeeze Is in Diesel, and Refiners Collect It
A refiner buys crude and sells gasoline and diesel. Its profit is the gap between the two, and that gap is widest in diesel because diesel is where supply is shortest.
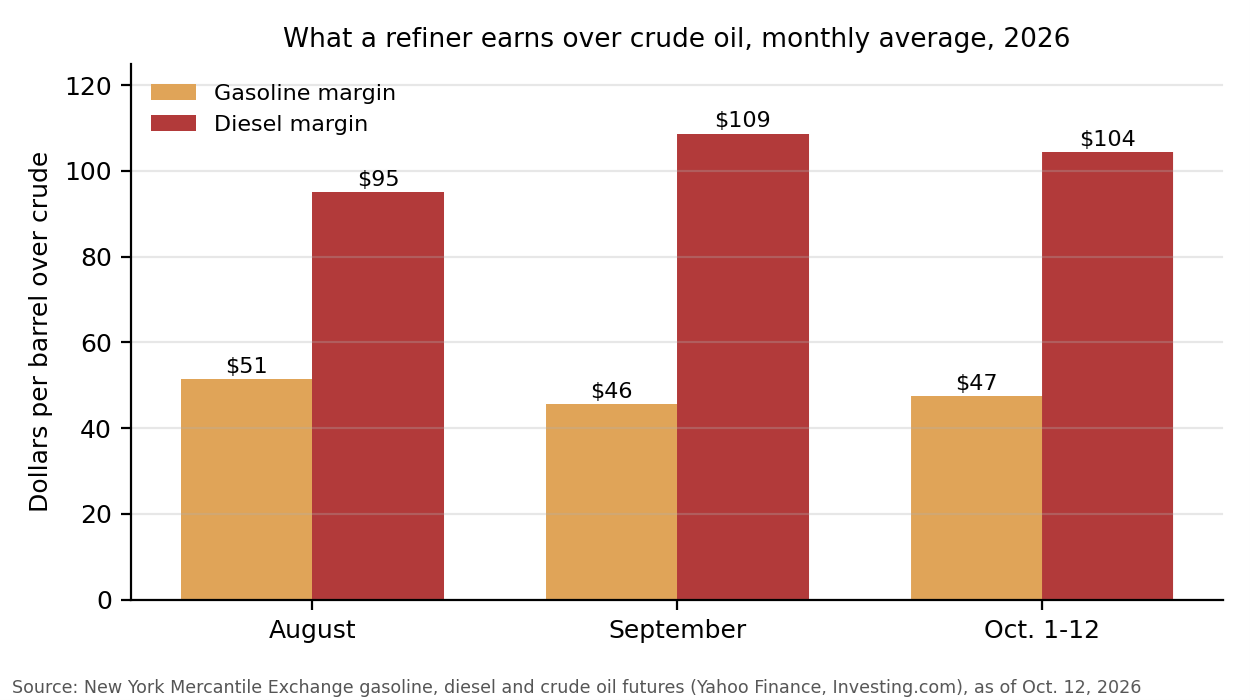
Diesel stocks on the East Coast were 32% below their five-year average in September, according to the U.S. Energy Information Administration. That shortage is what keeps the diesel margin near records even as crude eases.
The September inflation report is the same story from the other side. Energy accounted for the increase, while the rest of the basket added about the same as in August.
This "B+" BUY Is Expected to Report a Record Quarter on Oct. 22
Buy Valero (VLO) at the next close; the stock closed Tuesday at $456.
Valero earns the gap between what it pays for crude and what it gets for gasoline and diesel, and right now that gap is widest in diesel. It runs most of its refining on the Gulf Coast. Weiss rates it "B+," a BUY, with Growth, Efficiency and Solvency, its ability to pay its debts, all rated Excellent.
Its Gulf Coast refining margin in the third quarter ran about 56% above the second quarter's, according to figures cited in an Oct. 9 preview of refiner earnings.
The stock has outrun Wall Street's average target of about $383 to $402. The newest targets are higher: Wells Fargo raised its target to $485 on Oct. 14. That's about $29 above Tuesday's close, a potential gain of about 6%.
Valero pays you to wait with $1.20 a quarter, a yield of about 1%, and its policy returns extra cash to shareholders. Give it a year, with the first check at the Oct. 22 report.
Valero beat the S&P 500 in each of the last three big jumps in crude oil, and in most of them it kept beating it for the next three months.
What could work against it: margins this high draw a response. The Group of Seven nations agreed to release emergency oil stocks, focused on diesel, Washington eased limits on Russian diesel, and a damaged diesel unit at Valero's Port Arthur, Texas, refinery isn't due back until around year-end.
The Takeaway
What happened: September's inflation jump came mostly from gasoline, and a smaller surprise in everything else put a Fed hike back on the table for October.
What it means: The fuel squeeze is sharpest in diesel, and the refiners that turn crude into diesel are collecting it, while oil producers already trade near Wall Street's targets.
If fuel margins fall quickly, Valero falls with them; that is the risk you take.
Valero is the kind of idea my process surfaces; my AI Profit Accelerator portfolio holds the ones that pass its stricter, fundamentals-first test.
What to do today: Buy Valero (VLO) at the next close; the stock closed Tuesday at $456.
What We're Watching
First, Oct. 22. Valero reports a quarter analysts expect to show record margins. If management says margins have already rolled over this quarter, I would sell, and I will say so.
Second, the Gulf Coast margin. If it falls back toward the second quarter's level of about $30 a barrel, the reason to own the stock is gone.
Third, the other refiners. Marathon Petroleum and Phillips 66, both "B+," a BUY, have also run past their targets. What would make me buy them is a pullback after their own reports.
Fourth, the emergency diesel. If the Group of Seven release and the Russian supply bring diesel stocks back toward normal, Valero's best margin shrinks.
Take care,
AL Qureiyeh