 |
| By Sean Brodrick |
One of the best things about attending mining conferences is getting to kick the tires on companies in person.
I recently attended the Beaver Creek Precious Metals Summit in Avon, Colorado.
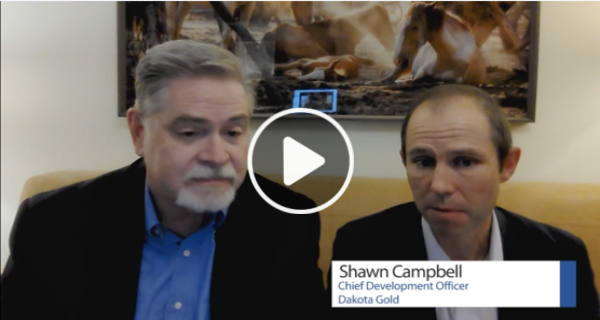
While I was there, I sat down with Shawn Campbell, Dakota Gold's (DC) chief development officer.
I interviewed him about the company's plans.
I’ll let him give you the briefing on the company in his own words …
This wasn't my first encounter with Dakota Gold, either.
Back in January, at the Vancouver Resource Investment Conference, I talked with Dakota Co-Chairman Robert Quartermain.
Quartermain is one of the first reasons I take this company seriously.
He founded Pretium Resources and led the development of the Brucejack gold mine in British Columbia. Newcrest eventually bought Pretium for about $2.8 billion.
In other words, Quartermain has done this before.
Now, he and the Dakota Gold team are trying to do it again — in one of the richest gold districts in American history.
Dakota controls roughly 50,000 acres surrounding the legendary Homestake District in South Dakota.
The old Homestake Mine produced around 40 million ounces of gold over more than a century.
Dakota Gold has progressed from exploration to developing its flagship Richmond Hill project into an open-pit mine.
Richmond Hill contains 3.65 million ounces of measured and indicated gold, plus another 2.61 million inferred ounces.
The ore grade is about 0.55 grams per metric tonne (g/t), which is about average for an open-pit mine and better than some profitable operations.
And the grade might improve.
Drilling at the project continues to deliver some terrific grades, including one recent intercept of 24.9 meters grading 5 g/t gold.
Inside that was a 1.5-meter interval running a whopping 60.82 g/t.
It’s Seen This Movie Before
Another thing I like about Richmond Hill is that Dakota is following a tried-and-true path.
Richmond Hill is being designed as a conventional open-pit, crushed-ore heap-leach operation.
Just down the road sits Coeur Mining's (CDE) Wharf Mine, which has successfully mined similar oxide gold using heap leaching for decades.
Dakota effectively has a working model sitting right in its backyard.
Management can see how this type of ore behaves, how it's processed and what it costs to mine.
And the preliminary numbers look GOOD.
An initial assessment estimated up-front capital of $384 million and life-of-mine all-in sustaining costs of just $1,047 per ounce.
At a gold price of only $2,350, the project generated an estimated after-tax net present value of $1.6 billion and a massive 55% internal rate of return.
Now the story is moving from “We've found a lot of gold” toward “Let's build a mine.”
Dakota has completed the drilling needed for its pre-feasibility study.
Dakota is targeting a feasibility study in 2027, potentially followed by construction in 2028 and production in 2029.
More Opportunities
Richmond Hill isn't Dakota's only rich project. It also owns the nearby Maitland project.
Maitland is targeting the kind of high-grade underground mineralization that made Homestake famous in the first place.
Dakota has experienced people, a big gold resource, rich grades, a proven mining model practically next door and a project steadily marching toward construction.
A Value Play
At $3,350 per ounce, the project's after-tax value is $2.9 billion to $3.7 billion, with returns of 99% to 107% per year.
That's roughly four to five times the current market value.
And news is on the way.
The Q4 2026 pre-feasibility study should turn resources into the company's first reserves.
It will add 30% more drilling data than the last resource estimate.
Lab tests showed up to 92% gold recovery, and the company chose a simpler design with a single leach pad.
Sure, there are reasons to be cautious.
Importantly, Dakota Gold has about $99 million in cash, while the mine will cost $384 million to build, so more dilution is likely unless the company secures a financing or streaming deal.
Also, it’s waiting on permits. Investor interest can turn away while that drags on.
Still, I believe it’s worth keeping on your radar. Here’s a weekly chart of Dakota Gold …
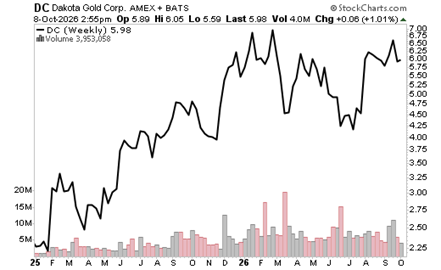
Dakota Gold is holding up very well despite gold’s recent pullback.
Not bad for a company that isn’t even producing gold yet.
Plenty of gold explorers hope they'll eventually become producing mines. Dakota Gold is getting much closer to actually becoming one.
All the best,
Sean
P.S. While Dakota should be on your radar, I have another opportunity you can act on today. It’s called Project Pheonix.