 |
| By Sean Brodrick Reviewed by: Jim Nelson |
I like owning stocks that pay me to hold them. Stocks I can count on to keep hiking those payouts. And I especially like to buy these stocks when they’re on sale.
Here’s my list of three beaten-down dividend champions that offer attractive income today — and the potential for bigger gains in 2027.
Specifically, I'm looking for four things:
- Dividend royalty. A company must be a Dividend Aristocrat, with at least 25 consecutive years of dividend increases and membership in the S&P 500, or a Dividend King, with at least 50 years of increases.
- A substantial discount. The stock should be trading well below its six-month high. I'm not interested in chasing stocks that have already enjoyed their big rallies.
- A decent yield. I want meaningful income while I wait for the stock price to recover.
- Growth ahead. There must be a credible reason to expect better business results in 2027.
That last requirement is important. A high dividend yield is no bargain if the underlying business is deteriorating.
My sweet spot is a financially established company with a long history of increasing dividends, temporarily depressed shares and improving prospects.
Here’s my short list of three companies that deserve a closer look.
No. 1: Genuine Parts — A Dividend King Preparing for a Breakup
Let's start with Genuine Parts Company (GPC), a business that has been rewarding shareholders for generations.
Genuine Parts is best known for NAPA Auto Parts, one of America's largest distributors of automotive replacement parts.
It also owns Motion Industries, which supplies industrial replacement parts, equipment and maintenance products.
The company has increased its dividend for more than six decades. That makes it a Dividend King — one of the most exclusive clubs in corporate America. There are only 58 U.S. stocks that earn that moniker.
Yet Genuine Parts’ stock has struggled, even though it pays a quarterly dividend of $1.0625 per share, or $4.25 annualized, despite being an established business with two potential growth engines.
The first is America's aging vehicle fleet.
The average age of vehicles on U.S. roads has climbed to a record 12.94 years. And the longer Americans keep their cars, the more money they generally need to spend maintaining them.
That means more demand for replacement parts, brakes, batteries, filters and other products sold through NAPA's extensive distribution network.
The second growth engine is industrial automation and reshoring.
As American manufacturers invest in new factories, upgrade existing equipment and bring production back home, Motion Industries stands to benefit from demand for industrial components and maintenance supplies.
And there are already signs of improving business momentum.
In the third quarter, Genuine Parts reported sales of $6.5 billion, up 4.2% year over year.
Adjusted earnings rose to $2.07 per share from $1.98 a year earlier, and management expects full-year 2026 adjusted earnings of $7.50 to $7.75 per share.
The company is also looking at approximately 4.5% to 5% revenue growth in 2027.
But there's an even bigger catalyst on the horizon.
Genuine Parts plans to separate its automotive and industrial businesses into two independent, publicly traded companies in the first quarter of 2027.
A separation would let each company pursue its own strategy, allocate capital more efficiently and potentially attract investors willing to pay higher valuations for a focused business.
Let’s look at the weekly chart …
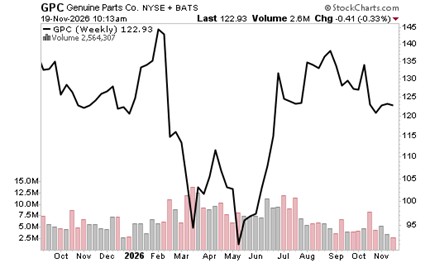
You can see that GPC is well off the high it hit in February, and then the next high it hit in August. It has been on a rollercoaster. But the beauty of this stock is that it pays you to wait.
I believe uncertainty about the spin-off is also weighing on GPC’s share price.
I’m happy to hold a stock that’s going to hand me shares of a spin-out company.
Genuine Parts offers an appealing combination: a long dividend history, exposure to durable replacement-parts demand and a potentially transformative corporate event.
No. 2: Archer-Daniels-Midland — A Dividend King Betting on a Recovery
My second pick is Archer-Daniels-Midland (ADM), one of the world's agricultural giants.
ADM buys, transports, stores and processes crops including corn, wheat and soybeans. It also produces vegetable oils, animal feed, specialty food ingredients and biofuel feedstocks.
It's an essential link in the global food supply chain.
And it's another Dividend King, having increased its annual dividend for more than 50 consecutive years.
But being essential doesn't mean being immune to economic cycles.
ADM has faced pressure from weaker agricultural processing margins, changing global supply conditions and company-specific accounting issues that have weighed on investor confidence.
The result has been a substantial decline from its recent highs.
ADM is a classic cyclical recovery candidate. And the recovery may already be underway.
On Nov. 3, ADM reported third-quarter adjusted earnings of $1.77 per share, with adjusted net earnings of $858 million.
Even better, management raised its full-year 2026 adjusted earnings forecast to $5.50 to $5.80 per share, up from its previous forecast of $5.15 to $5.60.
That's an encouraging development for a company whose profits have been squeezed by difficult agricultural markets.
One of the most important profit drivers for ADM is the crush spread — the difference between what it pays for crops such as soybeans and what it earns selling the resulting oil and meal.
When processing capacity exceeds demand, those margins get squeezed. That's been a major headwind.
But the latest results show how quickly conditions can improve.
Operating profit in ADM's Ag Services and Oilseeds segment more than doubled in the third quarter, climbing to $778 million from $379 million a year earlier.
Its crushing operations alone generated $311 million in operating profit, compared with just $13 million in the year-earlier quarter.
There's an opportunity in the company's Nutrition business. ADM produces flavors, specialty ingredients and other higher-value products for food and beverage manufacturers.
This business has experienced its own difficulties, but improving customer demand and a recovery from inventory destocking could support better results.
Let’s look at the weekly chart …
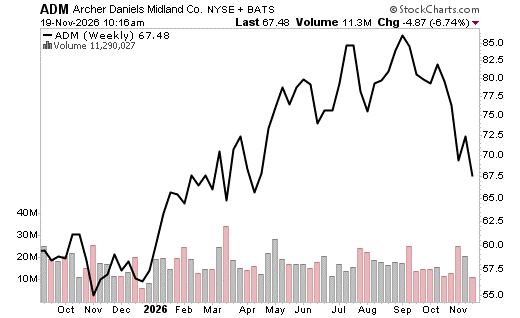
You can see that ADM is more than 20% off its September high; for investors with an eye on the longer term, that just fattened the dividend yield, which recently stood at 3.16%.
If processing margins continue recovering while the Nutrition segment improves, ADM's earnings could rebound significantly from depressed levels.
Analysts are already expecting 2027 revenue growth of 5% to 7%. If ADM is in the virtuous part of the cycle, growth could be even higher.
For income investors willing to accept some cyclical risk, ADM offers an opportunity to collect dividends while waiting for the agricultural cycle to turn.
No. 3: Realty Income — Monthly Dividends
Realty Income (O) is one of the best-known real estate investment trusts, or REITs, in America.
It calls itself The Monthly Dividend Company. And for good reason.
Unlike most companies, which distribute dividends quarterly, Realty Income pays shareholders every month.
It has increased its dividend annually for more than 30 consecutive years, qualifying it as a Dividend Aristocrat.
Realty Income owns more than 15,400 properties, many leased to businesses selling everyday necessities, including convenience stores, grocery stores and discount retailers.
Its tenants typically sign long-term net leases that require them to pay many of the property's operating expenses, including taxes, insurance and maintenance.
That helps Realty Income generate relatively predictable rental cash flow, and it uses that cash flow for a dividend yield of 5.6%, the highest of my three picks today.
So why has the stock been struggling? Interest rates.
Higher Treasury yields make income-oriented investments such as REITs less attractive relative to bonds.
They also raise financing costs, making it more expensive for property companies to acquire additional real estate.
Realty Income has felt that pressure. But there's a reason to expect continued growth in 2027. And its latest quarterly results provide some evidence.
On Nov. 2, Realty Income reported third-quarter adjusted funds from operations, or AFFO, of $1.12 per share, up 3.7% year over year.
AFFO is generally a more useful measure of a REIT's recurring cash-generating ability than traditional earnings per share.
Management also raised its full-year 2026 AFFO guidance to $4.45 to $4.46 per share.
Realty Income also invested $2.6 billion during the quarter, demonstrating that it continues to find opportunities to expand its enormous property portfolio.
Its international growth strategy is also accelerating.
The company expanded its European private-capital platform through a strategic joint venture with investment giant KKR, supported by an initial investment of €528 million.
That arrangement could provide another source of capital for acquisitions while allowing Realty Income to expand its presence in European real estate markets.
Its existing portfolio remains a powerful foundation. Occupancy has historically been around 99%, helping support steady rental collections.
Realty Income could grow AFFO per share by approximately 3% to 4% in 2027, supporting continued modest dividend increases.
That isn't explosive growth. But it doesn't have to be. If Realty Income delivers steady cash-flow growth, continues raising its dividend and benefits from more favorable interest rates, shareholders could enjoy both income and capital appreciation.
Let’s look at the weekly chart …
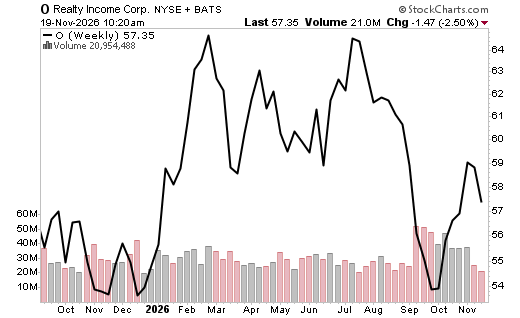
You can see that Realty Income is down more than 10% from the high it hit in July. But it’s also well off the low it touched in October and should zigzag its way higher.
The principal risk is that interest rates remain elevated, keeping acquisition financing expensive and REIT valuations under pressure.
Still, if you’re prioritizing dependable monthly income, Realty Income deserves serious consideration.
3 Different Paths to Dividend Profits
What I like most about these three stocks is that they don't depend on the same catalyst.
Genuine Parts offers a potential corporate breakup and value-unlocking opportunity.
Archer-Daniels-Midland offers a cyclical recovery in agricultural processing margins — one that appears to be gaining traction already.
And Realty Income offers a relatively high monthly dividend supported by long-term leases and steady cash flow.
All three have demonstrated a commitment to increasing shareholder payouts through good times and bad.
And all three offer potential upside if their businesses perform better in 2027.
My goal here isn't simply to collect a dividend. It's to get paid while waiting for the market to recognize value.
And that's why Genuine Parts, Archer-Daniels-Midland and Realty Income are three of my favorite dividend stocks right now.
Dividend investing isn’t for everybody. But if it’s your cup of tea, you can do a lot worse than buying these three stocks.
All the best,
Sean Brodrick
P.S. On Tuesday, you can hear how to supercharge that income.
In fact, Nilus Mattive just helped readers lock in a $948 payment using ADM shares two weeks ago. That’s on top of a $960 income payment back in September on that same stock.
He’ll show you how it works on Tuesday, Nov. 24, at 2 p.m. Eastern. Here’s how to see it live.