Housing Starts Slump: Why Grainger Beats Home Depot and Lowe's Now
 |
| By Gavin Magor Reviewed by: Leo Tavolaro |
If you've driven past a new subdivision lately, you may have seen the signs going up: price reduced.
Yesterday the builders told us why, as their confidence fell to its lowest level since 2012, and this morning the government confirmed they're breaking less ground.
Two weeks ago, I told you why the obvious "stay and fix it up" trade in Home Depot (HD) and Lowe's (LOW) wasn't the way forward.
The new numbers make that case stronger, not weaker.
And they point to where the money is still flowing while the builders pull back.
Here's where the money is going, and where it isn't.
Good News If You're Buying
In October, 43% of builders cut prices to bring in buyers, the highest share since at least 2020.
The average cut held at 6% for a seventh straight month.
And 65% offered sales incentives, which makes 19 months running with six in 10 or more builders sweetening the deal.
So if you're shopping for a home, the builder may be the most motivated seller in town.
The Catch Is the Loan
The average 30-year mortgage rate was 7.40% as of Oct. 15, according to Freddie Mac, up from 6.27% a year ago.
On a $400,000 loan, that's the difference between paying about $2,468 a month in principal and interest and paying about $2,770.
That's roughly $300 more every month, or about $3,600 a year, before taxes and insurance.
A 6% price cut helps, but it doesn't erase that.
Bad News If You're Staying Put
Families who locked in a low rate years ago still have every reason not to move.
Mortgage applications fell another 2.7% in the week ending Oct. 9, as the average contract rate the Mortgage Bankers Association (MBA) tracks edged up to 7.50%.
Two weeks ago, I said the big remodels would stay on hold until mortgage rates fall well below 7%.
Since then, rates have moved the other way.
The Builders Just Put Down Their Shovels
The National Association of Home Builders (NAHB)/Wells Fargo Housing Market Index fell three points to 29 in October, a reading we haven't seen since June 2012.
Economists had expected 31.
Builders pointed to pricier mortgages, pricier financing for their own projects, rising costs for materials and diesel fuel, tariffs, and crews they can't fully staff.
Over a third said immigration enforcement had shown up in their local markets in the past month.
This Morning's Proof
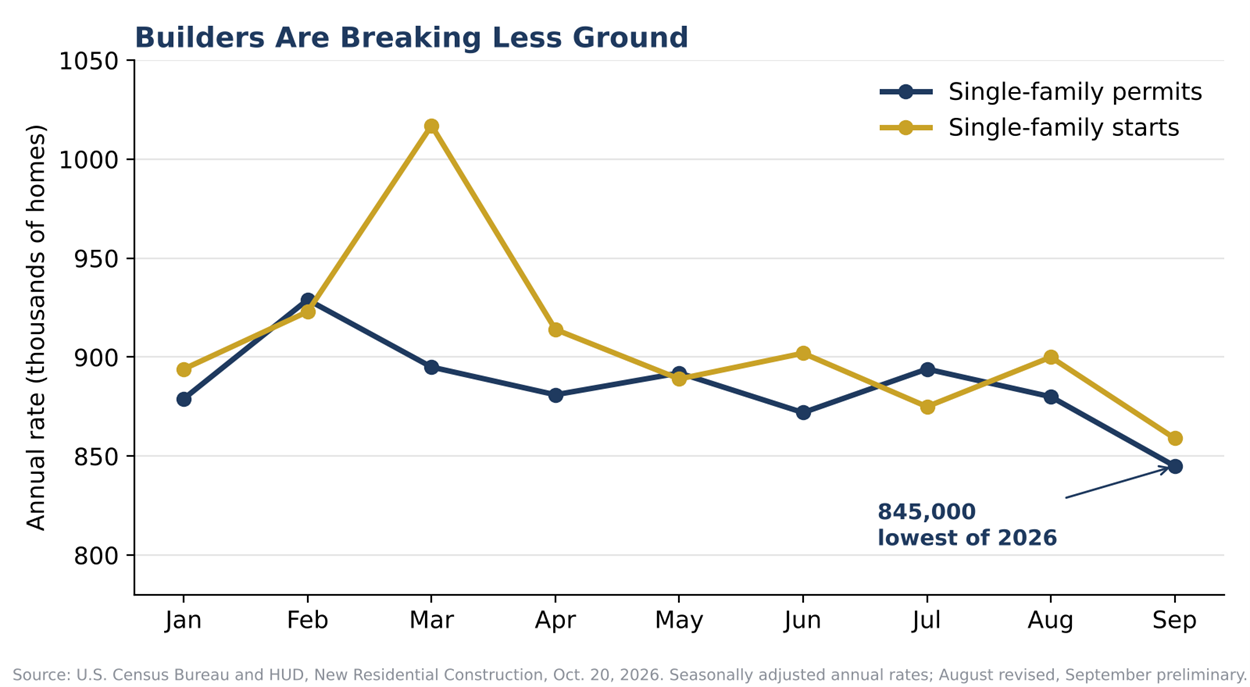
Single-family housing starts fell 4.6% in September to an annual rate of 859,000 homes.
Single-family building permits fell 4% to 845,000, the lowest reading of the year.
I'd pay the most attention to permits.
They come straight from local permit offices and carry no sampling error, so they're the cleaner read on what builders plan to do next.
And here's the detail that stood out to me.
At the end of September, 279,000 homes had been authorized but not yet started, up 9.8% from a year earlier.
That's the pile of unused permits.
The builders have the paperwork.
What they don't have is enough buyers who can carry a 7.40% mortgage.
The Numbers Behind the Pivot
The industrial suppliers are telling a very different story from the builders.
Grainger (GWW) sells the supplies that keep factories, warehouses and commercial buildings running.
In its second quarter, its sales rose 10.3% to $5 billion.
On a daily, organic, constant-currency basis, they grew 13.7%.
Earnings per share rose 20.5% to $12.01.
And management raised its full-year outlook, now calling for sales growth of 8.4% to 10%.
In the Weiss Ultimate Portfolio, which I edit, we hold another industrial supplier that reported last week.
Its sales to factories and to commercial construction customers both grew by double digits.
Factories Busy, Subdivisions Quiet
The broader economy backs that up.
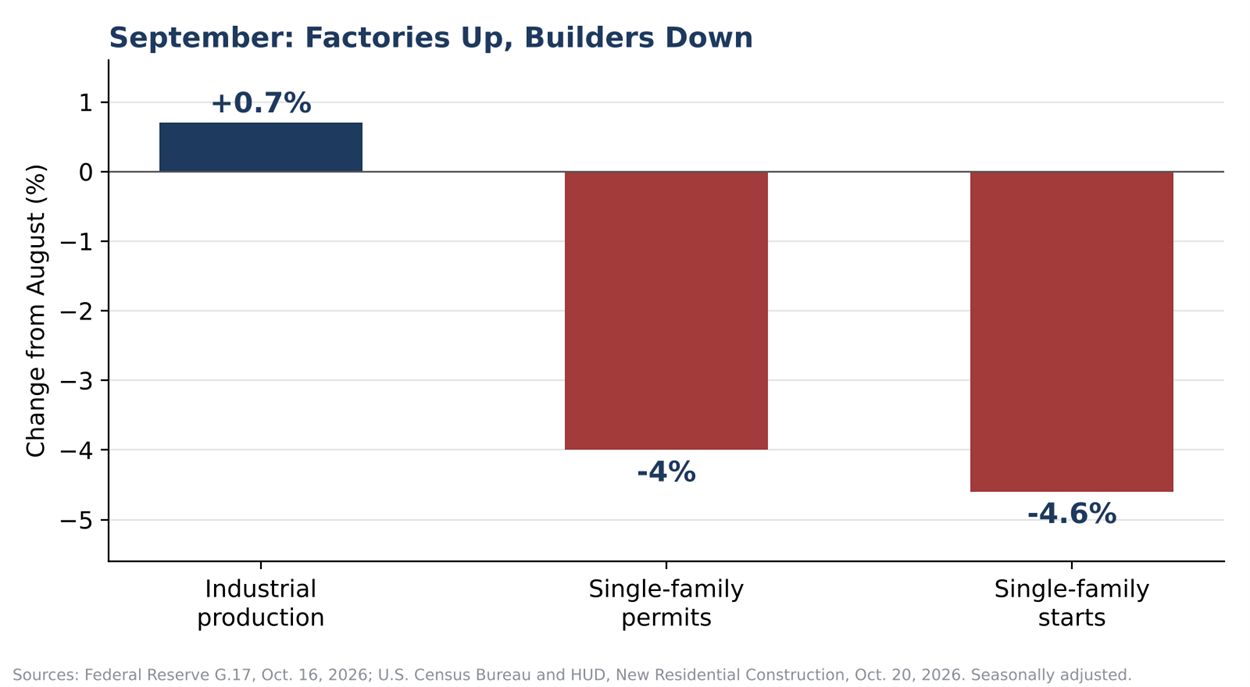
Industrial production rose 0.7% in September, after edging up 0.1% in August, according to the Federal Reserve (Fed).
In the same month, single-family permits and starts both fell.
So the builders are putting down their shovels just as the factories and commercial job sites pick theirs up.
Home Depot Bounced, the Rating Didn't
Home Depot has rallied 6.58% over the past week, and it closed yesterday at $309.88, well above its Oct. 1 low of $277.15.
If you held on rather than selling into that low, as I suggested, you've enjoyed the bounce.
But a bounce isn't a turnaround.
Home Depot is still rated a C, a HOLD.
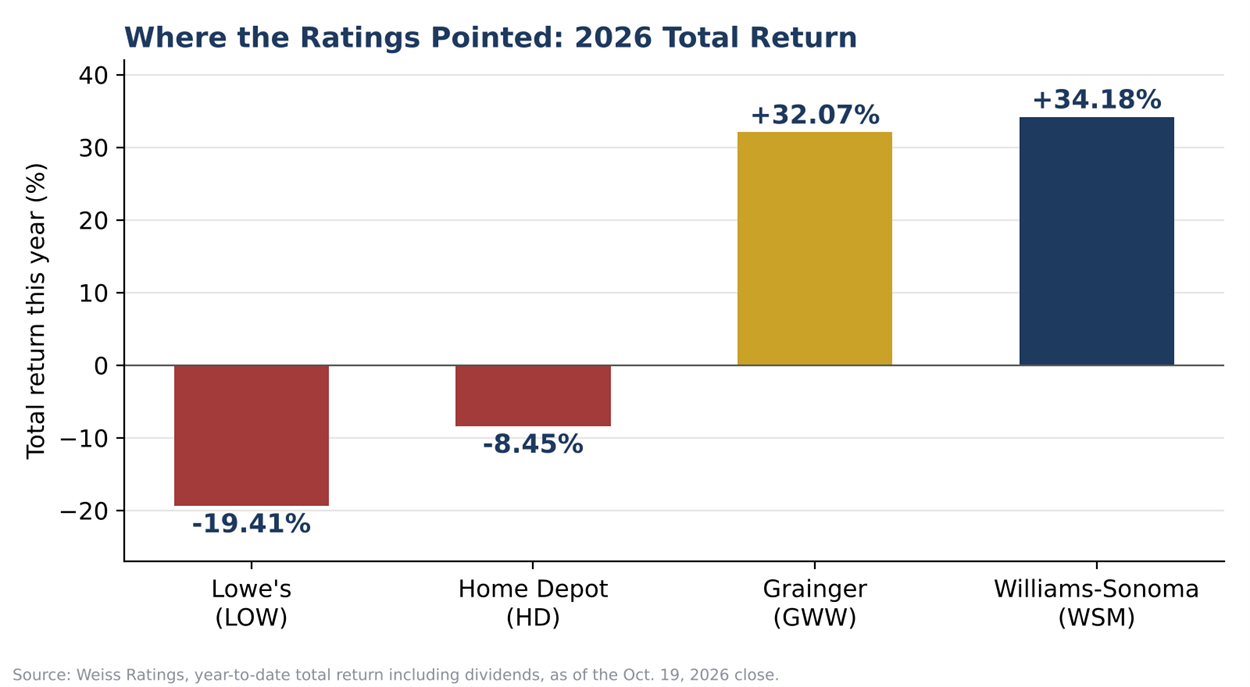
Lowe's is still a C-, a HOLD, and it's down 19.41% this year.
My view hasn't changed: don't add to either one until the rating improves.
Why Builders Pulling Back Doesn't Help
You might think fewer new homes would push more families to fix up the ones they have.
For the small jobs, that's probably true, and a homeowner who can't move still buys a furnace filter.
But the big remodels are tied to borrowing costs and to buying and selling homes.
With rates at 7.40% and builders marking down new homes, neither of those is coming back soon.
Who's Getting Paid, Who's Waiting
Williams-Sonoma (WSM) was our pick two weeks ago, and it still earns a B, a BUY.
It sells to the same homeowners as Home Depot and Lowe's.
Its shares set a new 52-week high on Oct. 16, and they've returned 34.18% this year.
The Outside-Housing Names Held Their Grades
Two weeks ago, I said the best housing-related stock right now may not look like a housing stock at all.
All four names I pointed to still earn a B- or better.
Grainger, which I'll come back to, still rates a B, a BUY.
Trane Technologies (TT) rates a B, a BUY.
EMCOR (EME) rates a B-, a BUY.
The fourth is a stock we hold in the Weiss Ultimate Portfolio, so I won't name it here.
I will tell you it has since earned an upgrade.
Among the Builders, the Buyer Matters
Price cuts tell you which builders can hold the line.
Toll Brothers (TOL) sells to wealthier buyers who depend far less on a mortgage, and it earns a B-, a BUY.
Lennar (LEN) has chosen to keep building and selling at whatever price the market will bear.
It's rated a D+, a SELL, and it's down 25.57% this year.
Let the Ratings Do the Sorting
Every rating in this report came straight from the live Weiss Ratings pages this morning.
Weiss Ratings Plus puts that same work in front of you, with real-time ratings, instant alerts on upgrades and downgrades, and exclusive analysis.
It's how you'd spot an upgrade the day it happens, without waiting for the next report.
And it's how you'll know the day Home Depot or Lowe's finally earns a better grade.
Click here to see what Weiss Ratings Plus can do for you.
Grainger: The Supply Closet Behind America's Factories
Two weeks ago, Grainger was one of the four companies I listed that made their money away from your kitchen.
It still earns a B, a BUY.
Not only does Grainger earn a high Weiss rating, but it also fits this market.
Its customers are businesses, not homebuyers, and the factories among them are getting busier as homebuilding slows.
Grainger closed yesterday at $1,318.06, and it has returned 32.07% this year, including dividends.
The shares are up over the past week and the past month, too.
It also returned $341 million to shareholders in its second quarter through dividends and buybacks.
For my part, I expect Grainger to keep growing through this housing slump, because its customers keep their doors open whether or not new homes get built.
Grainger is my pick for new money in this market.
And if you're a Weiss Ultimate Portfolio member, you already own a stock in the same line of work that we expect to keep growing right along with it.
What I'm Watching
- Freddie Mac's next weekly mortgage survey on Thursday, for any move back toward 7%.
- The Fed's Oct. 27-28 meeting, and what it signals for mortgage rates.
- New home sales for September on Oct. 27, to see whether the price cuts are bringing in buyers.
- Home Depot's and Lowe's third-quarter reports in November, for any pickup in customer transactions.
- Any upgrade in the Weiss rating on Home Depot or Lowe's, still the first real sign the fix-it trade is turning.
- Williams-Sonoma's third-quarter report in late November, to see whether its market-share gains hold up.
Bottom Line
Those "price reduced" signs are good news if you're buying a house.
They're not a reason to buy Home Depot or Lowe's.
Put new money where the ratings point, starting with Grainger.
Cheers!
Gavin