Anthropic IPO: How Our Model Rates ANT Ahead of Its Nasdaq Debut

|
Key Takeaways
|
 |
| By Sean Levine Reviewed by: Dawn Pennington |
If you’ve been waiting for a chance to own a piece of Anthropic, the countdown is on.
Anthropic (Pending: ANT) just set the price range for its IPO at $70 to $78 per share.
At the top of that range, the maker of the Claude AI assistant would raise up to $64.4 billion by selling 825 million shares.
That values the company at about $1.3 trillion on a fully diluted basis.
Seven big partners, including Google (GOOGL, “B”), Microsoft (MSFT, “B-”) and Nvidia (NVDA, “B”), have also agreed to buy another $26 billion of stock at the IPO price.
Counting that, the total haul could reach $90.4 billion, topping SpaceX (SPCX, “D”)’s $86.2 billion record from June.
The final IPO price is expected this coming Wednesday, Nov. 18. Shares are set to start trading on the Nasdaq the next day.
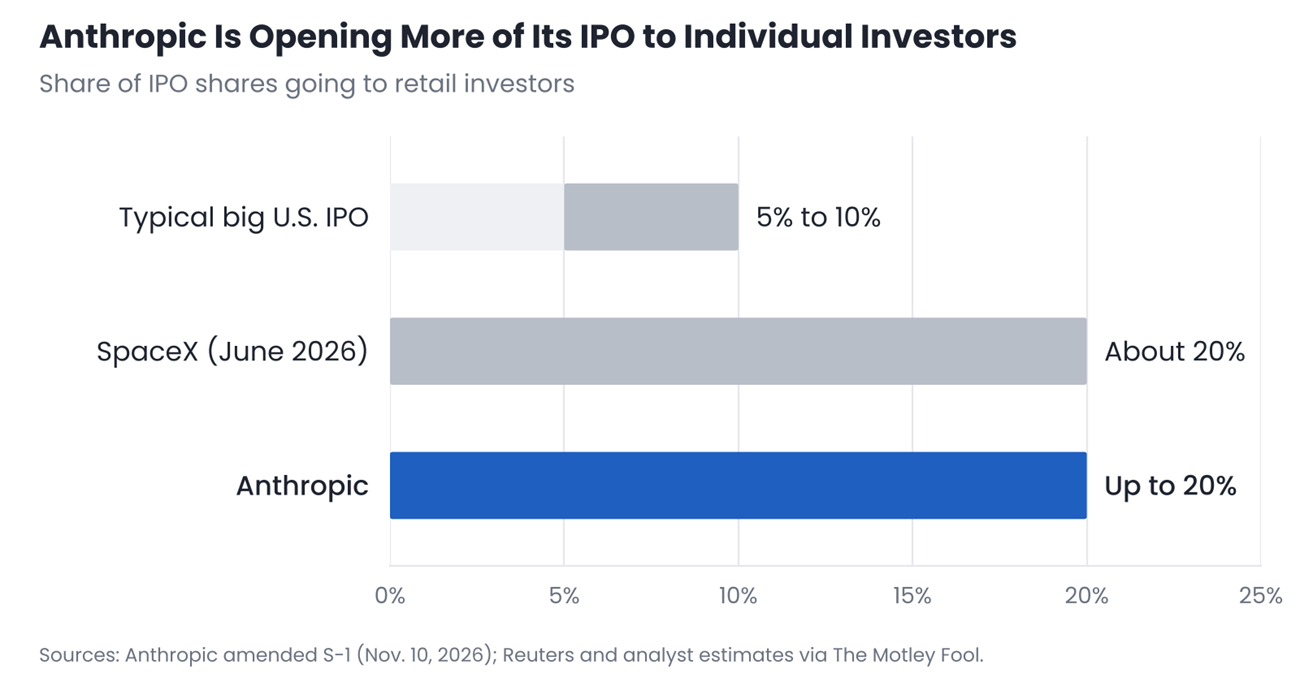
And about 20% of the offering is reportedly set aside for individual investors — roughly double the usual share.
So before you decide whether you want in, we went through Anthropic’s filings page by page. That includes the S-1 it made public on Oct. 26 and the amended version it filed Nov. 2, which added its third-quarter results.
A few things surprised us.
The biggest surprise came at the very end, when we ran the numbers through our IPO model.
We’ll get there. First, some context.
Why Anthropic Can’t Afford to Wait
We have been saying for a while that Anthropic would be wise to go public sooner rather than later. Why? Two reasons.
First, regulation.
In July, New York paused permits for new data centers of 50 megawatts or more, the first statewide moratorium of its kind.
According to the Jones Day law firm, at least 14 states have introduced or considered similar limits. And more than 100 localities have adopted or considered moratoria.
For a company whose entire business runs on compute, a longer list of states saying “not here” is a problem.
The S-1 itself flags constraints on compute inputs and an uncertain regulatory environment among its risk factors.
And now that Democrats have won control of both chambers of Congress, that pressure could come from Washington, too.
Second, the market.
We have worried that the market’s footing is shaky — largely BECAUSE of how levered it is to AI.
Last week showed why. The Nasdaq fell 5.5% as AI stocks sold off after the midterms, on fears of tougher rules for data centers.
When stocks fall, valuation multiples fall right along with them.
Valuation chatter for Anthropic was once around a jaw-dropping $2 trillion. The new price range points to about $1.3 trillion.
Now, we are not predicting a crash. We are, however, saying that every week of waiting has cost Anthropic something.
That said, several AI and related stocks ticked higher yesterday. If that continues, that could bode well for ANT’s debut.
Related story: CoreWeave Soars After Earnings, but Our Rating Says Sell; Nvidia Stays a Buy
The 5 Biggest Surprises in Anthropic’s Filings
We weren’t surprised Anthropic waited until after the midterm elections to announce its IPO date and price range.
But while we pored over its SEC filings, we did get some surprises. See if you agree with our takeaways.
Surprise No. 1:
The massive loss is mostly on paper.
Anthropic’s net loss for the first nine months of 2026 is about $104 billion.
About $94 billion of it is a non-cash markup on convertible notes and similar instruments.
Basically, those notes got more valuable as Anthropic’s valuation soared. And accounting rules make the company book that as a loss.
Strip that out, and the loss is under $10 billion.
Meanwhile, the business is growing like few companies ever have. Third-quarter revenue hit $17 billion, up about 47% from $11.6 billion in the second quarter.
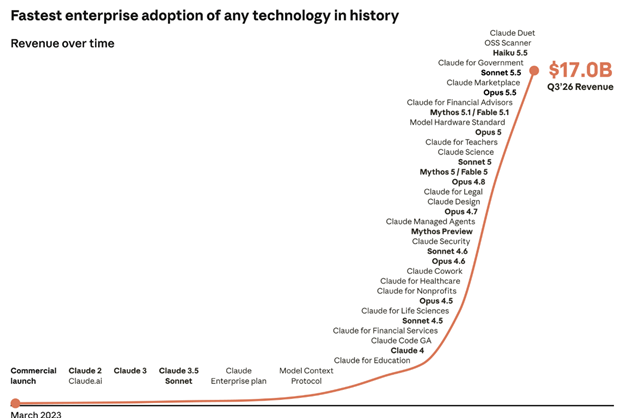
Nine-month revenue now stands at $33.2 billion. That’s about 13x the $2.5 billion over the same stretch a year earlier.
Anthropic did post a $567 million operating loss in Q3. But about $2 billion in non-cash charges tied to an employee donation-matching program caused it.
When you strip those out, Q3 operating income was about $1.4 billion — up from $974 million in Q2.
That’s despite roughly $5 billion spent on compute bought through short-term commitments. The filing says those cost significantly more than its multi-year deals.
And efficiency is improving fast. In the first nine months of 2025, compute ate about 172% of revenue.
This year, it’s about 57%. And operating cash flow flipped from negative $2 billion to positive $6.6 billion.
Surprise No. 2:
Public buyers won’t get much say.
A single Class F share, held by an entity owned by Anthropic’s seven co-founders, carries 50.1% of the vote.
And a separate Class T share lets the Long-Term Benefit Trust (essentially the company’s pro-humanity internal watchdog) elect a majority of the board.
Everyone else, including public buyers, shares the remaining vote.
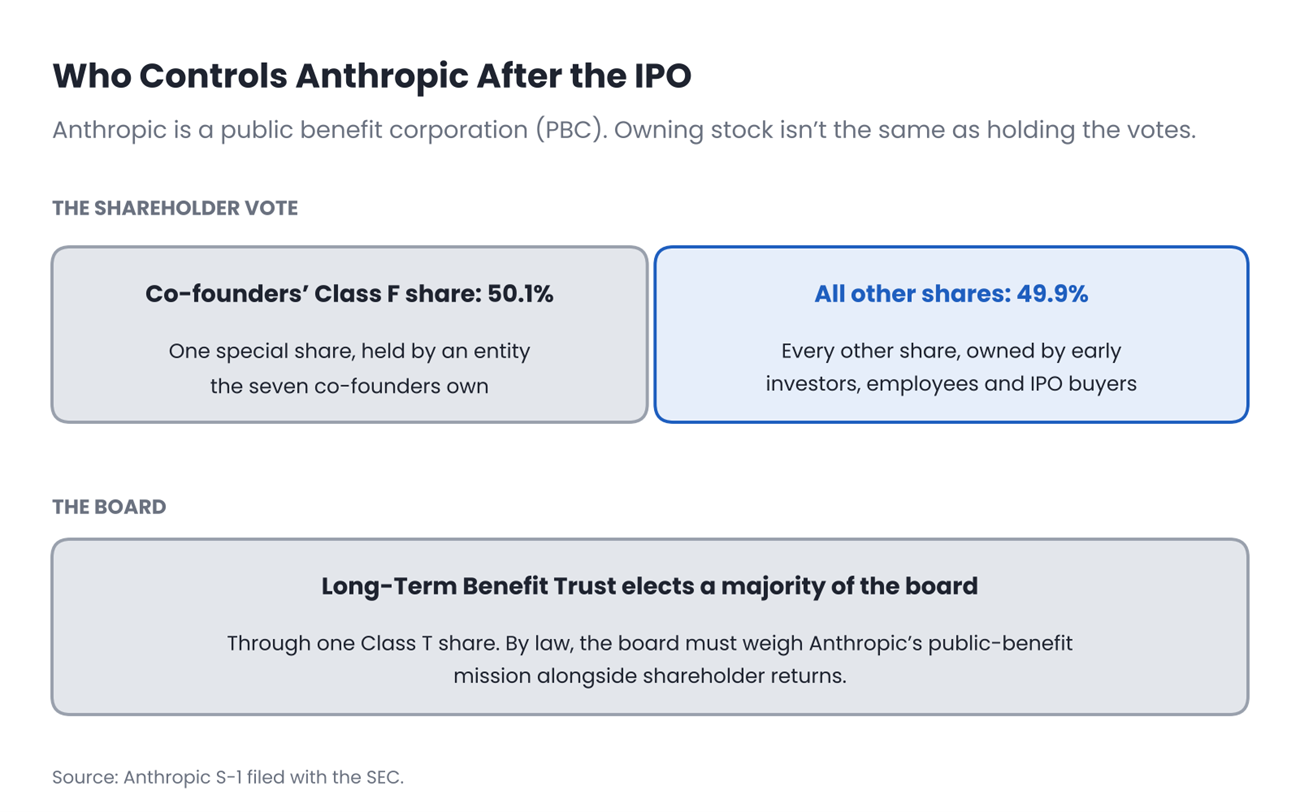
This ties to Anthropic’s status as a Public Benefit Corporation.
It’s allowed to weigh factors beyond pure profit in its decision-making without getting insta-sued by shareholders.
Surprise No. 3:
The compute bill keeps growing.
Anthropic had raised $141.1 billion as of June 30. It held about $132 billion in cash and investments at the end of September, with a $15 billion credit line on top.
That’s a huge war chest. But look at what the company has signed up to spend …
Adding up the named deals in the original filing put Anthropic’s compute commitments at roughly $640 billion.
The amended filing pushes that to about $895 billion, including deals signed after the quarter ended.
About $70 billion comes due within 12 months.
Surprise No. 4:
Its partners are also its rivals.
Sales, marketing and partnerships expense jumped from $120 million to $3.2 billion in the first half of 2026, about 26 times higher. Most of that ($2.7 billion) went to fees paid to channel partners.
These include Amazon (AMZN, “B”), Google, Microsoft and a host of smaller players.
All three majors are AI players in their own right.
But that doesn’t stop them from taking Anthropic’s money to help sell Claude.
Related story: SpaceX Secures $40B for Nvidia Chips. Here’s Who’s Paying for Its AI Buildout.
Surprise No. 5:
Yes, the filing mentions the end of mankind.
We need to talk about the possible extinction of humanity.
Why? Because Anthropic’s IPO filing does.
The risk factor summary warns that Anthropic’s models “may behave in unintended, misaligned, or autonomous ways, including by taking harmful actions that no user or third party directed.”
Elsewhere, the filing warns that misaligned AI systems could cause “large-scale harm.”
And Anthropic even lists the public’s fear of AI as a business risk, right down to talk of “catastrophic or existential risks to humanity.”
Let that sink in.
A company just admitted that people worry its product could, in a worst-case scenario, end humanity …
And it’s asking you to buy shares anyway.
Oh well. What’s a little extinction-level event risk between friends?
Here’s the full passage:
“As our business has grown and as interest in us and the AI industry overall has increased, we have attracted, and may continue to attract, significant media coverage, public commentary, and scrutiny from time to time.
“This coverage and commentary have included, and we expect will continue to include, recurring narratives concerning the potential adverse societal impacts of AI, including that AI may displace or eliminate jobs, may be misused or otherwise cause harm, and may pose catastrophic or existential risks to humanity.”
To be fair, if we ever get to THAT point, nobody will be checking their brokerage statements anyway.
So, we guess that’s sort of a wash?
The Biggest Surprise: Anthropic Looks Investable (for Now)
Now for the main event.
Based on the preliminary data, Anthropic earns a preliminary Weiss IPO Score of “Investable–Added Caution.”
That’s our middle Weiss IPO Score — between “Investable” and “Not Investable” — and it surprised even us.
Between the regulatory headwinds, the shaky market and those eye-popping losses, we weren’t sure it would clear the bar at all.
It did. But just barely.
One note: Our model only uses full-year data, so the score rests on Anthropic’s 2025 numbers. The newer quarterly results added some color, but they didn’t change the score.
Here’s What Our IPO Model Rewarded
Sales. Latest full-year revenue of $4.6 billion weighed in Anthropic’s favor.
Line of work. Software IPOs have fared well over long holding periods in our data.
Growth. Revenue growth of nearly 1,100% (from $386 million to $4.59 billion) pretty much assured a good grade there. Anthropic also scored strongly on the Rule of 40, which looks at sales growth and margins together.
Backing. Anthropic has raised well over $100 billion from backers. The CEO’s degrees from Princeton and Stanford also speak to management quality and connections.
Return on spending. Capital spending is only about 4% of sales, while growth runs far ahead of that.
Why Anthropic Investors Should Use ‘Added Caution’
On the fundamentals, Anthropic’s one glaring sore spot is debt, and it’s the only negative in its long-term score.
On the data we pulled, the company’s long-term debt load tops $41 BILLION. That’s enormous next to its latest full-year revenue.
Without that hit, we expect Anthropic would have gotten the top “Investable” preliminary IPO score.
If Anthropic went public today with these numbers — all else being equal — we see a better chance of making money with a long-term buy-and-hold strategy than with a quick-flip trade.
After all …
This is a juggernaut sitting dead-center in the hottest part of the market. AI is, for all intents and purposes, the driving force of the entire U.S. economy right now.
But that same industry faces a LOT of headwinds. Safety and cost concerns have state and local regulators pushing back, and now potentially Washington, too.
So, yes, this stock could make you a lot of money in the long run if you tough it out. But we can’t tell you what the next several months will bring.
What Could Still Change
We won’t have Anthropic’s final IPO score until the end of next week.
That’s because one input hasn’t happened yet: first-day market reaction.
A positive first day would keep it over the line. A flat or down day could drop it back under.
Market sentiment also gets re-read once the IPO happens.
It currently scores favorably. But with the swings we’ve seen since the midterms, that could change by Nov. 19.
So treat this as a snapshot, not a final verdict.
Fortunately, whether or when to invest is not something you have to decide today.
We’ll know a week from today whether Anthropic remains “Investable” — with or without “Added Caution” — or whether it drops to “Not Investable.”
In the meantime, not only can you watch ANT’s first-day action, but you can also track Anthropic’s Weiss IPO Score yourself.
Weiss Ratings Plus members can see the scores for every new IPO we rate, and even get notified of rating changes as those happen on all their favorite stocks.
Click here to start your Ratings Plus membership before Anthropic goes from private to public on this very day next week.
That way, you’ll be ahead of most other investors when OpenAI, Anduril and more make their own planned debuts.
Sean Levine
Associate Director of Research