Micron Trades at 7x Earnings. Why Aren't Investors Rushing In?

 |
| By Gavin Magor |
Micron Technology (MU) just beat Wall Street on every line that matters, and its stock went down.
That isn't a verdict on Micron.
It's a verdict on what investors now demand from a stock when a government bond pays more than 5%.
Related story: What 5% Treasury Yields Are Really Telling Us, and Where the Opportunity Sits
What Micron Delivered
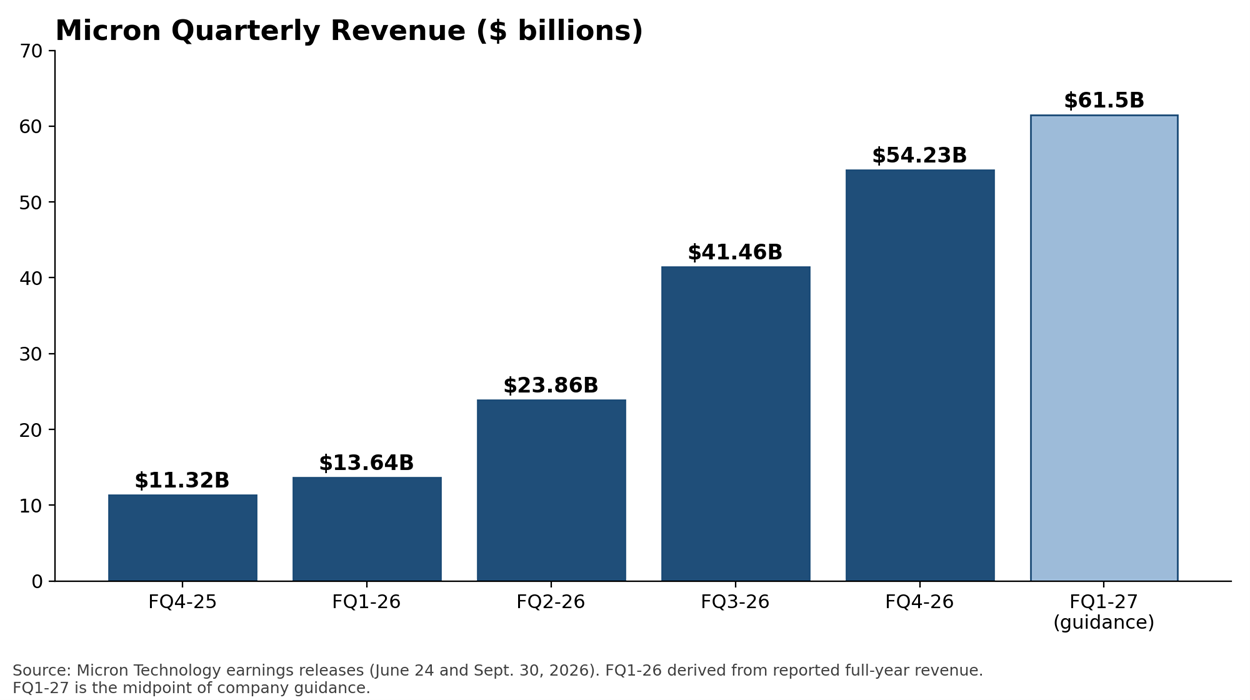
Revenue for the fiscal fourth quarter, which ended Sept. 3, came in at $54.23 billion.
That's almost five times the $11.32 billion Micron reported in the same quarter a year ago.
Adjusted earnings per share (EPS) were $33.42, against the $31.61 analysts polled by LSEG expected.
Adjusted gross margin reached 87%.
The outlook was even better.
Management guided first-quarter fiscal 2027 revenue to about $61.5 billion and adjusted EPS to $38.15, both above the $57 billion and $35.40 analysts were looking for.
Micron also said it expects memory supply to stay tight through calendar 2027 and 2028.
Why a Great Quarter Wasn't Enough
Shares ended Wednesday essentially flat at about $1,065, ahead of the report.
MU gained 3% Thursday after the news. But shares dipped after-hours.
Three things explain the shrug.
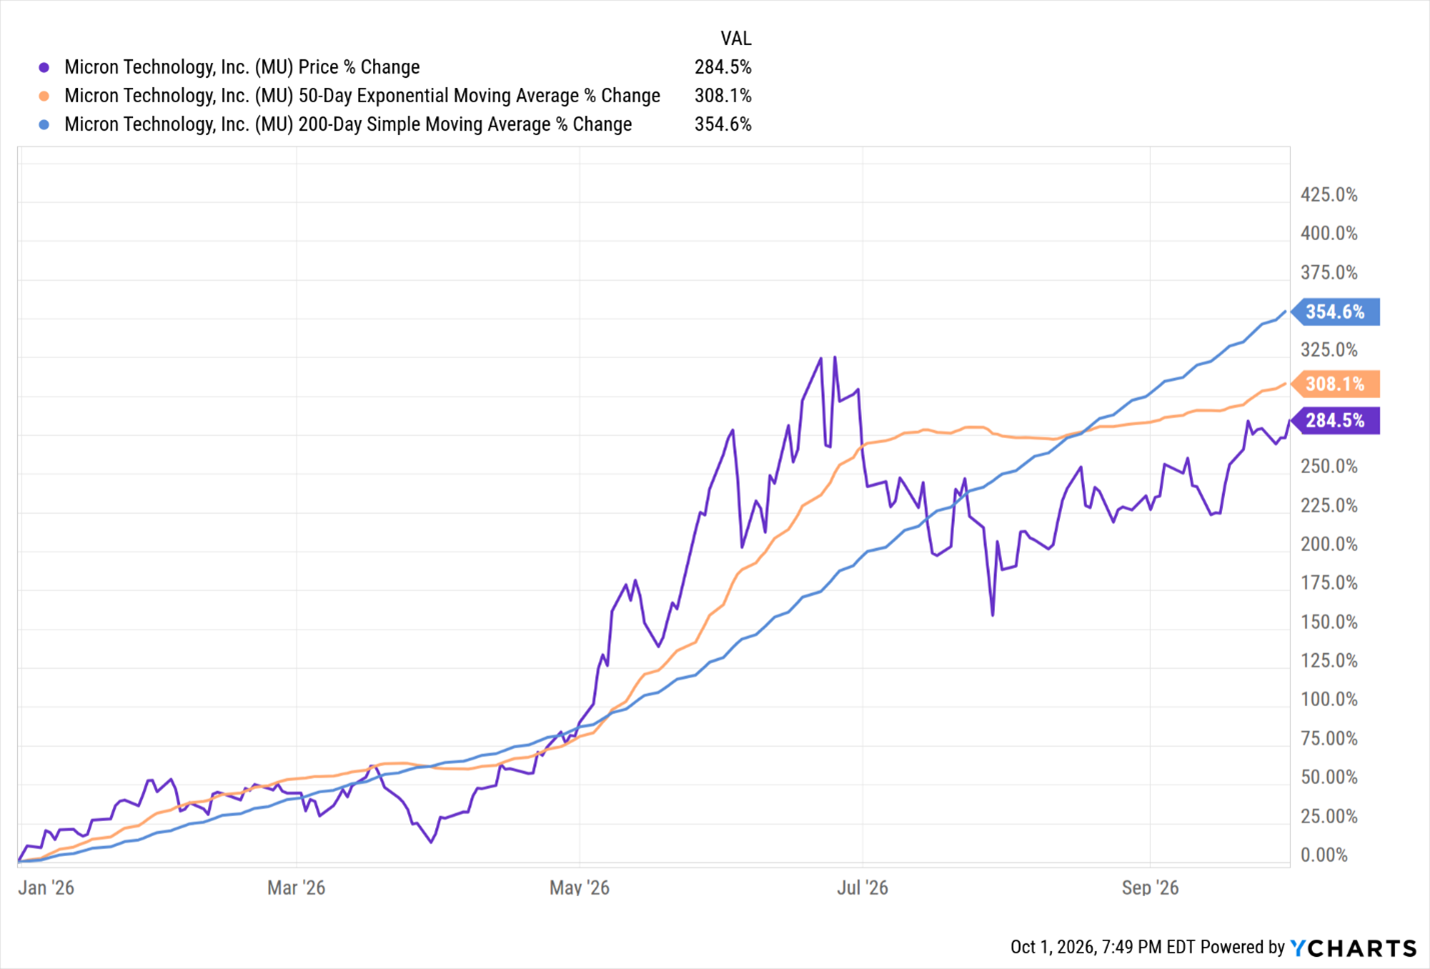
First, the bar was sky-high: The stock has returned 555% over the past year, with a 284% gain so far this year.
Second, the adjusted gross margin guide of 86.25% is a touch below the 87% just reported, and Micron plans to raise capital spending in fiscal 2027.
Management tied the softer margin to higher worker pay.
Third, this stock has a habit.
Last quarter, it rose 15.74% on earnings day, then gave back 19.61% over the following week.
So, investors are in no rush to chase it.
The 5.3% Competitor
The bigger story sits in the bond market.
The 10-year Treasury yield sits above 5% this morning.
Yesterday’s Institute for Supply Management (ISM) survey added fuel, with its prices index jumping to 77.9 from 71.1.
For years, investors bought stocks partly because bonds paid so little.
Wall Street even had a name for it: "There is no alternative," or TINA.
At 5.3%, there is an alternative.
And artificial intelligence (AI) is part of the reason.
Heavy borrowing to build AI infrastructure is adding to bond supply and pushing yields higher.
This week, the Bank of England (BoE) cited an estimate of about $450 billion in global AI-related debt issued by early September, more than double all of 2025.
It also warned that AI valuations remain vulnerable to a sharper correction than the one in July.
Here's the Twist
Micron isn't one of the borrowers.
It ended the fiscal year with $73.48 billion in cash and investments against roughly $5.2 billion of debt.
Its quarterly interest income rose to $575 million from $146 million a year earlier.
Higher rates are working for Micron's balance sheet, not against it.
The real exposure is its customers, many of whom are borrowing to buy its chips.
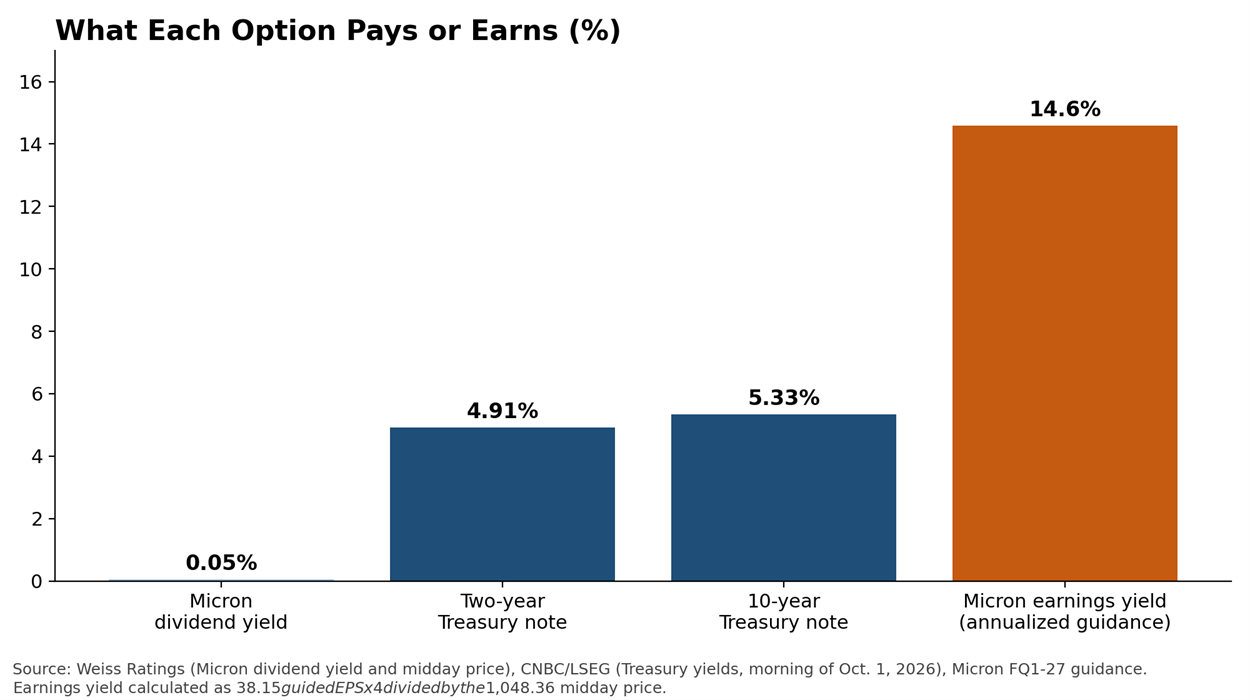
If you annualize next quarter's EPS guidance, Micron trades at about seven times earnings.
That's an earnings yield near 14%, almost three times what the 10-year note pays.
In other words, the market is pricing these profits as a cyclical peak, not a new floor.
What We'd Do Now
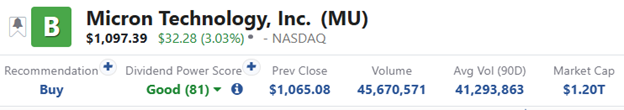
Micron holds a Weiss rating of “B,” a BUY.
We see no reason to walk away from a BUY-rated company that just raised its outlook.
But how you hold it matters more than it did a month ago.
If Micron has grown well beyond the weight you intended, trim it back to target.
Put the proceeds in the two-year Treasury note, which yields about 4.9%.
That captures most of the 10-year's yield with far less price risk if rates keep rising.
If you don't own Micron yet, build the position in stages rather than all at once.
Its beta of 2.35 means it has tended to move more than twice as much as the market, and that cuts both ways.
Whilst a semiconductor fund might look like the easier way to own the AI chip trade, the ratings point elsewhere.
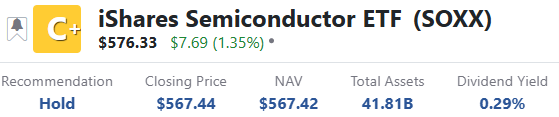
The iShares Semiconductor ETF (SOXX) carries a Weiss rating of “C+,” a HOLD.
In this market, quality is concentrated, so we prefer owning the leader directly over owning the whole basket.
For my part, I expect Micron to trade on its earnings rather than on excitement until the 10-year backs away from 5%.
That's not a bad trade to be in.
Key Items We're Watching
- Whether the 10-year yield breaks above 5.379%, its April 2002 high. A move past that level would take us back to dot-com-era borrowing costs.
- Friday's September jobs report. A strong number keeps the FOMC leaning toward higher rates.
- Micron's gross margin against its 86.25% guide. Any slippage would test the tight-supply story.
- AI customer financing. If the borrowing the BoE flagged starts to slow, chip orders could follow.
Bottom Line
Micron beat on every line that matters, and the stock still didn’t soar.
That isn't a warning about Micron.
It's a reminder that a 5.3% Treasury yield now competes with every stock you own.
Keep the BUY-rated winner, trim it to size, and let the two-year note pay you while you wait.
Cheers!
Gavin