Anthropic's Nov. 19 IPO Has a $104 Billion Twist

 |
| By Jurica Dujmovic Reviewed by: Beth Canova |
The company behind Claude is preparing to go public.
Which means investors are about to get a closer look at what it costs to build an artificial intelligence business at extraordinary speed.
And the math isn’t as straightforward as you’d expect. Especially with the sky-high valuations the AI giant has been posting.
Because they only tell the first half of the story. How the market responds after the IPO will tell the rest.
And the details in Anthropic’s (Pending: ANT) updated filing should help us sketch out the details while we wait.
My colleague Juan Villaverde wrote earlier that crypto and AI are likely to be the next tech dream team. So, what impacts one sector … will ripple into the other.
Which means Anthropic’s headline-stealing IPO is worth paying attention to for every crypto investor.
Anthropic’s Headline Numbers
Anthropic has set an estimated IPO price range of $70 to $78 a share. Though confirmation of an exact price is expected to come on Nov. 18 — one day before it’s expected list.
At the top of that range, the company would be valued at roughly $1.4 trillion on a fully diluted basis, according to Reuters. That calculation includes potential shares from instruments such as stock options and restricted stock.
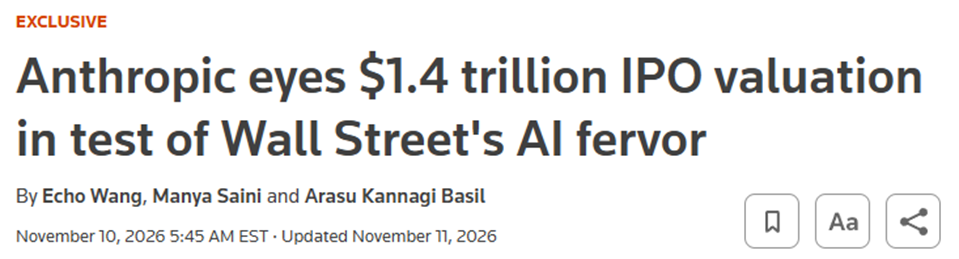
At the $78 top end, the full public sale would bring in approximately $64.4 billion before expenses.
A company doesn’t reach that kind of valuation without a story about enormous future growth. And Anthropic’s sales growth has certainly made investors pay attention.
It reported nearly $17 billion in revenue in the third quarter. That’s up from about $1.4 billion in the same period a year earlier.
Revenue for the first nine months of 2026 was $33.2 billion, compared with $2.5 billion a year earlier.
By the end of October, Anthropic said its revenue run rate — which takes recent activity and annualizes it — had reached about $81 billion. To be clear, this figure acts as a snapshot of how fast the business was running. It is not a guarantee of sales over the next year.
Anthropic earns money when customers use its AI models and through subscriptions. In the first nine months of 2026, about 79% of revenue came from usage-based services.
That can be a powerful business when customers find more work for Claude to do.
But it also means revenue can change with how much customers actually use the service.
Not only that, but serving those customers takes computing power. Which can get costly and eat into the company’s bottom line.
And that’s the part the headlines haven’t covered as much.
The Deeper Story Is Messier … and More Optimistic
Anthropic reported a $567 million operating loss for the third quarter, after an operating profit in the preceding quarter.
That’s a rough pill to swallow at first glance.
But the number’s a little less ominous when we look at what’s behind it.
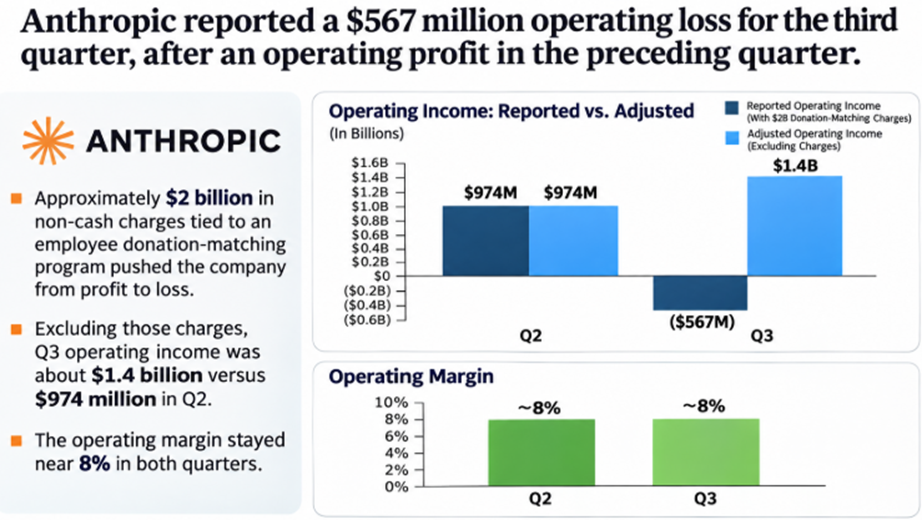
About $2 billion in non-cash charges tied to an employee donation-matching program swung the company from the black to the red. Strip that out and Q3 operating income was about $1.4 billion, up from $974 million in Q2.
The margin held at roughly 8% in both quarters.
And that Q3 number would have been solidly positive despite roughly $5 billion going to compute bought on short-term commitments, which the filing says costs significantly more than its multi-year deals. (More on this in a moment,)
The filing also makes note of the $104 billion net loss for the first nine months of 2026.
That’s a scary number … until you see that roughly $94.3 billion came from changes in the fair value of convertible notes and related financial instruments.
Those accounting changes are a major part of the reported loss and should be understood before treating the figure as money spent running Claude.
So, what are the continuing costs on the table? Well, Anthropic’s prospectus describes approximately $900.9 billion in purchase and lease commitments as of and after Sept. 30.
Pretty much all of that is connected to computing and infrastructure.
The bill stretches across many years. Anthropic expects approximately $70.7 billion to come due in the 12 months following Sept. 30, and about $451.6 billion to be incurred before the end of 2030. The rest is expected between 2031 and 2045.
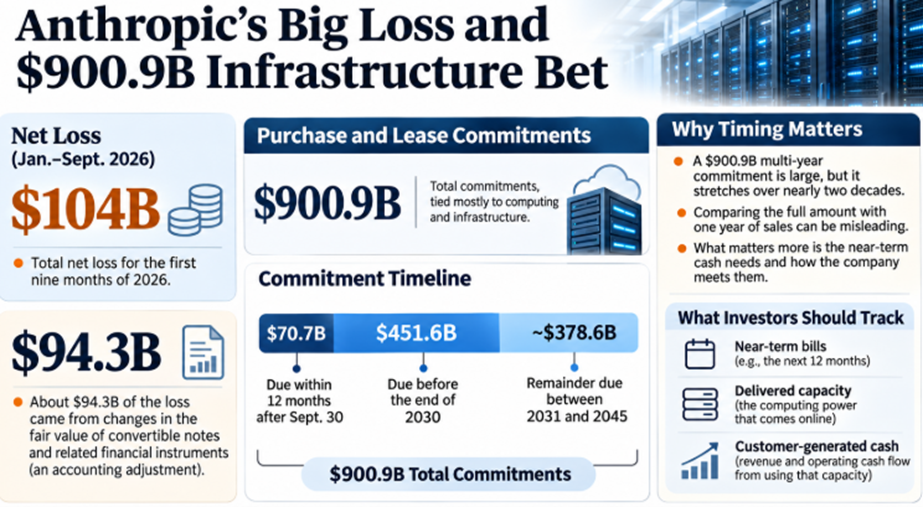
That is a very large commitment for a young company. But the time frame matters.
Comparing the entire multi-year amount with a single year of sales won’t tell us if Anthropic can pay its next bill. Instead, we need to watch which one is due next, the capacity actually delivered and the cash customers generate as they use it.
Additional AI Financing
The company has raised substantial financing to support its growth.
As of Sept. 30, it held about $95.6 billion in cash and cash equivalents and $36.3 billion in short-term investments. It also had access to a credit facility, subject to its terms.
Then there is the money expected alongside the IPO.
Google, Nvidia (NVDA, "B"), Advanced Micro Devices (AMD, "C"), Broadcom (AVGO, "B-"), Micron (MU, "B-"), Microsoft (MSFT, "B-") and Taiwan Semiconductor Manufacturing Company (TSM, "C+") have agreed, subject to conditions, to buy a combined $26 billion of nonvoting Anthropic shares in a separate private placement immediately after the public offering closes.
Google and Nvidia have each said they’d invest $10 billion.
These companies may seem like competitors on the surface. But they occupy different places in the AI supply chain.
Google and Amazon, for example, are existing investors and providers of computing services to Anthropic. And Nvidia makes the graphics processors used throughout the industry.
Anthropic’s filing also describes access to Nvidia-powered computing through several providers, including Microsoft.
Those connections give the companies a stake in Anthropic’s success from more than one direction. And they give you a less direct way to get a piece of the IPO An investor can own a piece of the AI developer, supply infrastructure that helps it operate, or both. Each agreement has its own terms, and the announced investment figures do not establish how many dollars will flow back to any particular supplier.
Bottom Line
Anthropic has shown that customers are willing to spend heavily on AI. And it’s also revealed how much capital it takes to run an AI company, let alone grow one.
The equation is tough to balance. Which means each of us will have to do the math to decide whether we think it’ll pay off.
The IPO will be the final test.
It’ll reveal in the open market just how much investors are willing to pay for that growth while the company commits to years of computing costs.
The result will matter to not just to anyone interested in trading the IPO or investing in Anthropic.
This IPO comes with support from some of tech’s biggest players. With their involvement, anyone interested in the broad tech sector should pay attention.
They also give investors who don’t want to deal with IPO volatility another way to gain indirect access to Anthropic.
And since crypto will likely be the infrastructure behind AI payments — as Juan explained yesterday — anyone interested in the networks building those rails should also watch closely.
Best,
Jurica Dujmovic