AI Stocks Sold Off After OpenAI’s Revenue Reset. Why Alphabet Held Up.

 |
| By Al Qureiyeh |
If you own AI stocks, the past week probably felt like the "AI bubble" finally showed up in your account.
Reuters reported last week that OpenAI, the maker of ChatGPT, told investors its yearly revenue pace was almost $50 billion, after earlier signaling close to $70 billion.
Then on Monday, the chief executive of Broadcom (AVGO) said money, not chips, is now the biggest limit on AI growth.
The International Monetary Fund warned Tuesday that an AI correction "could be global."
But look at what actually fell.
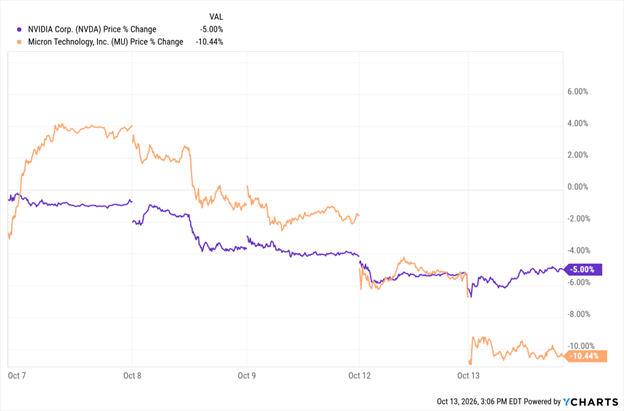
If you own chipmakers such as Nvidia (NVDA) or Micron (MU), you lost about 5% to 7% in a week. Meanwhile, Alphabet (GOOGL), Microsoft (MSFT) and Amazon (AMZN) rose.
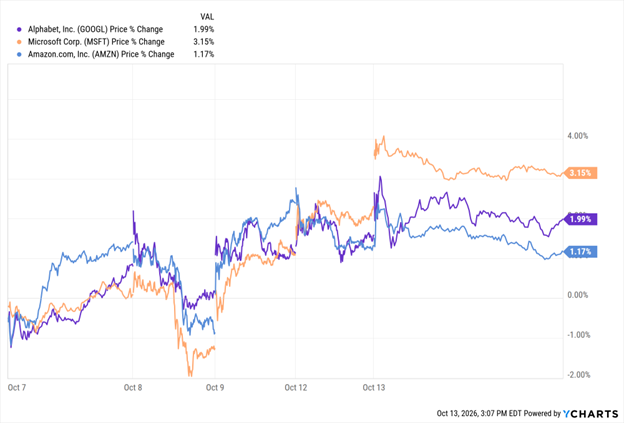
The market isn't selling AI …
It is selling the builders and their suppliers.
And it’s keeping the companies that sell AI to paying customers.
I'd own the best of those.
What Happened
The worry is who pays for the buildout.
Oracle (ORCL) and CoreWeave (CRWV) are building data centers largely for AI labs, and both borrow to do it.
Over the past year, Oracle spent about 1.6 times the cash its business brought in on data centers and equipment.
About half of Oracle's order backlog is OpenAI.
So when OpenAI's revenue came in below what it had signaled, the question became whether the builders get paid — and whether they keep ordering chips.
Since I suggested Nvidia and the Technology SPDR (XLK) on Sunday, Nvidia is down about 2% and the fund slightly, while the S&P 500 is up slightly.
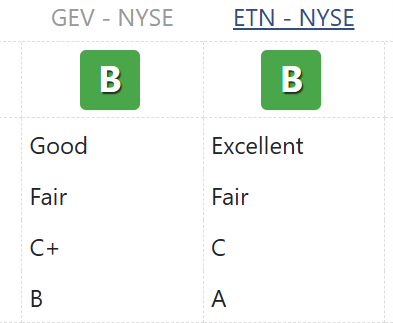
Eaton (ETN) and GE Vernova (GEV) from Oct. 7 are down a bit, too, but not enough to change their “Buy” ratings.
If you avoided Oklo (OKLO) and NuScale Power (SMR) when I said to, you sidestepped a 16% drop in each.
Why the Bubble Worriers Are Half-Right
Most of what is being written about AI right now is bearish.
There is a lot to look forward to when it comes to AI’s promised capabilities. In the meantime, two of the worries are real.
First, debt.
The IMF says the biggest cloud companies, such as Amazon, Alphabet and Meta, now sell about 10% of all corporate bonds issued worldwide by companies with strong credit ratings.
That’s up from less than 1% in 2024. It warns that this much borrowing could make any shock worse.
Second, one customer.
When a builder's orders lean on a single AI lab, that lab's revenue becomes the builder's risk.
Where the crowd is wrong is demand.
Anthropic — the lab behind Claude — took in more revenue than OpenAI in the second quarter, according to Reuters. And Bloomberg reports OpenAI still expects to reach $70 billion in revenue by year-end.
People are paying for AI.
The question is which companies collect.
Weiss Still Rates the Chipmakers and the Platforms ‘Buys’
The Weiss stock ratings split these companies the same way.
Weiss rates the chipmakers in this sell-off a “Buy.”
- Nvidia and Micron "B+,"
- Broadcom "B," and
- Advanced Micro Devices (AMD) "B-."
Their businesses are sound; their customers' funding is the risk.
The platforms rate as “Buys,” too:
- Alphabet and Amazon "B," and
- Microsoft "B-."
The builders rate lower, with Oracle at "C," a HOLD.
Then there's CoreWeave.
Weiss rates it "D-," a SELL, and over the past year it spent nearly three times the cash its business brought in on data centers and equipment.
Avoid CoreWeave.
The Selling Started With the Borrowers, Then Reached Their Suppliers
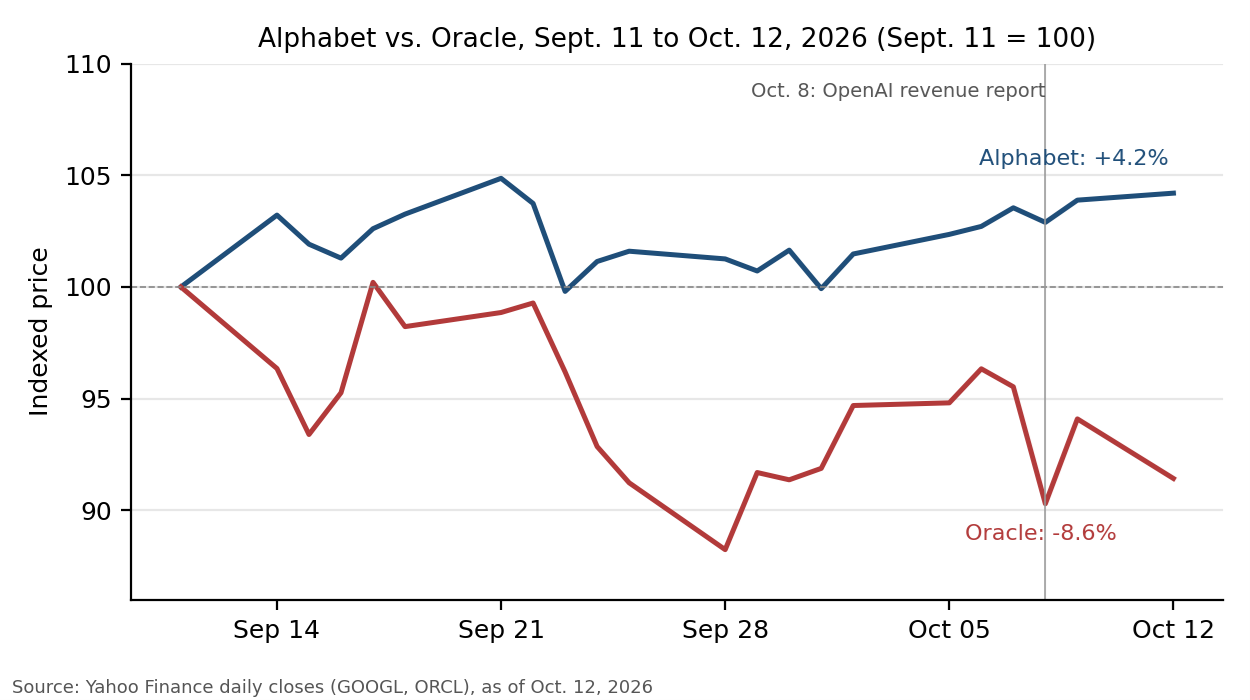
Over the past month, investors sold the builders that borrow while the chipmakers still rose.
Over the past week, the selling reached the chipmakers that sell to those builders.
That includes Nvidia and Micron.
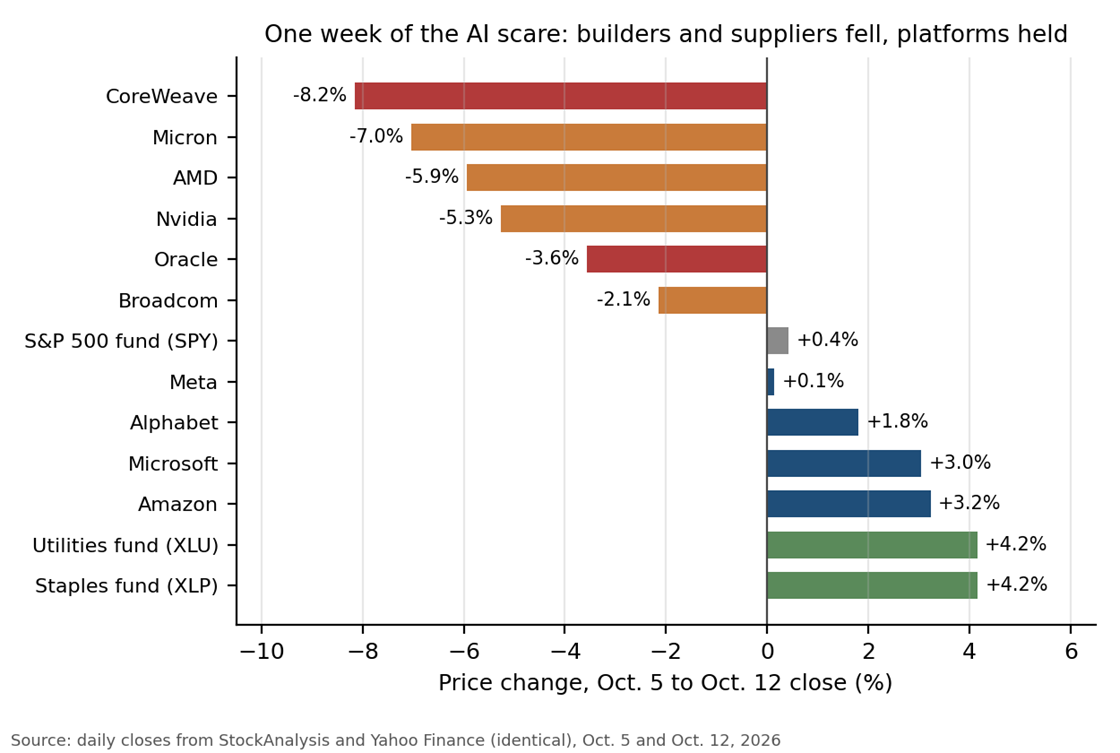
The platforms held up.
They sell AI to paying users and businesses, and most of them pay for the build-out from their own cash.
Over the past year, Alphabet's business brought in more cash than it spent on data centers and equipment. And it holds far more cash than debt.
Investors Also Bought Safety
The Consumer Staples SPDR (XLP) and the Utilities SPDR (XLU) did best of all.
But if investors were simply fleeing tech, the platforms would have fallen, too.
They didn't.
The AI Platform I'd Own
Alphabet has the numbers to back up … and sustain … its high rating.
It sells AI through Search, its cloud and its Gemini assistant to customers who already pay.
It also backs Anthropic, the lab now out-earning OpenAI.
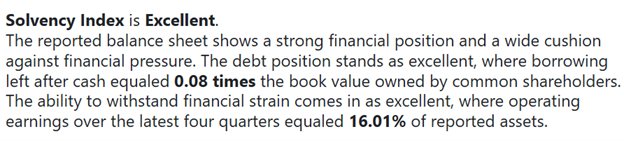
Weiss rates Alphabet "B," a “Buy,” with Growth, Efficiency and Solvency — its ability to pay its debts — all rated Excellent.
Monday's closing price of $353 was about $73 below the average Wall Street target.
That target, around $426, suggests a potential gain of about 21% from current prices.
The dividend is a token 22 cents a share per quarter. So, the case rests on growth, not the payout. Give it a year, with the first check at its next quarterly report.
In three chip-stock sell-offs between November 2025 and early June 2026, Alphabet beat the S&P 500 twice. It lagged in the steeper July slide, so this is a tendency, not a rule.
What could work against it: Alphabet borrows too, and in the second quarter its spending ran ahead of the cash its business brought in. Most of that quarter's reported profit came from paper gains on companies it has invested in, so if the value of those stakes falls, so does its reported profit.
The Takeaway
After an OpenAI revenue report and warnings about AI debt, the companies building AI and then their chip suppliers fell, while the platforms that sell AI held up.
What it means: The bubble worry is about who gets paid, not whether people use AI, and the platforms with paying customers and more cash than debt are on the right side of it.
A broad AI sell-off would still pull Alphabet down with everything else; that is the risk you take.
Alphabet is the kind of idea my process surfaces; my AI Profit Accelerator portfolio holds the ones that pass its stricter, fundamentals-first test.
What you can do today: Buy Alphabet, which closed Wednesday at $353.78. Avoid CoreWeave, which closed at $77.81.
What We're Watching Next
First, Microsoft. It reports on Oct. 28, the first of the big platforms. If it says customers are paying for AI faster, the case for the platforms gets stronger.
Second, Alphabet's own report. If its spending again runs ahead of the cash its business brings in, I would sell, and I will say so.
Third, the chip makers. Nvidia, "B+," a BUY, reports on Nov. 18. If the builders find the money, the chip makers should recover first.
Fourth, Amazon, "B," a BUY. It held up, but it spends more than its business brings in and has agreed to invest billions of dollars in OpenAI. What would make me buy it is cash flow catching up with spending.
Take care,
AL Qureiyeh